Guides & Resources
The RBA Just Hiked Again: How Much More Can Mortgage Holders Take?
The RBA has raised the cash rate to 4.6%.
Explore what higher rates mean for mortgage repayments, property prices and Australian households.

The Reserve Bank of Australia (RBA) has raised the cash rate by another 25 basis points to 4.6%, adding further pressure to Australian households with mortgages.
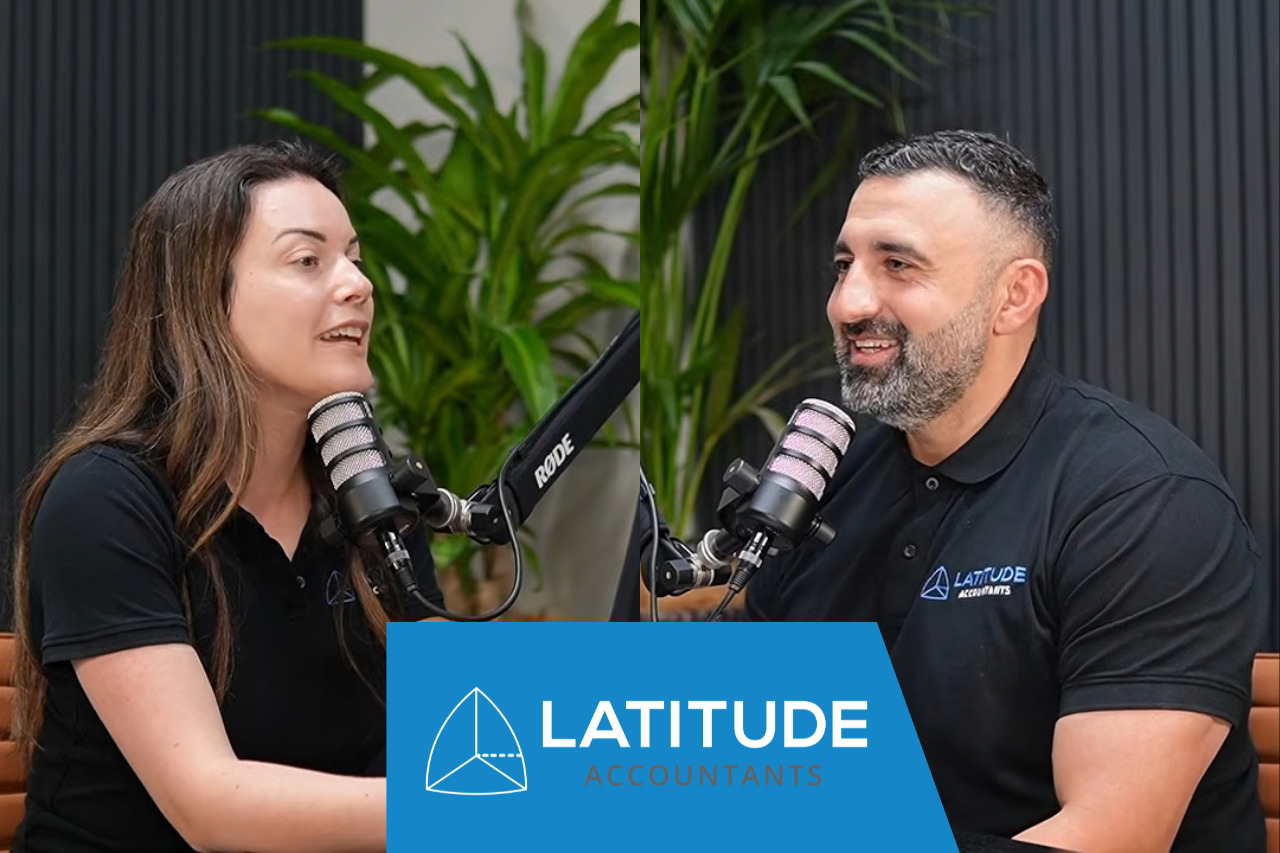
In this episode of The Account Rant, John Saade sits down with Catarina Santini to discuss what another rate increase could mean for mortgage holders, property prices and the broader Australian economy.
The discussion comes at a time when inflation remains elevated, while households are already dealing with higher living costs and increased mortgage repayments.
For borrowers, the key question is simple: how much more financial pressure can households absorb if interest rates remain higher for longer?
What Does a 4.6% Cash Rate Mean for Mortgage Holders?
Another 25-basis-point increase may appear relatively small, but its impact becomes more significant when added to previous rate rises.
During the discussion, John and Catarina consider how rising rates affect household cash flow and the difficult choices mortgage holders may now face.
For borrowers, higher interest rates can mean:
- Larger monthly mortgage repayments
- Less disposable income
- Greater pressure on household budgets
- Reduced capacity to save or invest
- Increased reliance on refinancing or restructuring
- Greater risk of selling property if repayments become unaffordable
John notes that repeated increases can create a substantial cumulative impact. Across multiple rate rises, the additional monthly repayment can become hundreds of dollars higher than it was previously.
For households already dealing with rising costs for groceries, utilities, insurance and other essentials, another increase can make balancing the household budget significantly more difficult.

Could Extending Your Home Loan Term Provide Relief?
One strategy discussed in the episode is extending the length of a mortgage.
For example, a borrower with a 20-year loan might consider refinancing or restructuring over a longer period to reduce their required monthly repayments.
The Potential Benefit
Extending the loan term can provide immediate cash flow relief.
Lower required repayments may give a household more room in its monthly budget, potentially helping the borrower manage higher interest rates without immediately selling the property.
The Long-Term Cost
However, there is an important trade-off.
A longer mortgage term generally means paying interest over a longer period. While monthly repayments may become more manageable, the total cost of the loan can increase over time.
This means extending a mortgage should be considered as a cash-flow management strategy rather than a way of making higher interest rates disappear.
Borrowers should assess the long-term financial consequences before restructuring their home loan.
Could Higher Interest Rates Put More Properties on the Market?
Another concern raised in the discussion is the potential effect of higher borrowing costs on the property market.
When mortgage repayments increase, some homeowners may find that maintaining their current property becomes increasingly difficult. If rates remain elevated, this could contribute to more properties being listed for sale.
The episode also discusses existing weakness in property prices across some Australian capital cities.
A combination of:
- Higher mortgage repayments
- Higher household expenses
- Reduced borrowing capacity
- Falling or weaker property prices
- Increased financial pressure
could create challenges for property owners and investors.
However, the effect will vary between households and markets. Borrowers with substantial financial buffers may be able to absorb higher repayments, while highly leveraged households may have less flexibility.
Why Is Inflation Driving the RBA’s Decisions?
A major part of the discussion centres on the RBA’s inflation mandate.
The RBA has been focused on bringing inflation sustainably back towards its target range. When inflation remains elevated, higher interest rates can be used to reduce demand across the economy.
Higher borrowing costs can encourage households and businesses to reduce spending, which can eventually ease pressure on prices.
However, the impact is not immediate, and the costs are not distributed evenly.
Mortgage Holders Feel the Impact Directly
John and Catarina discuss whether it is fair that mortgage holders can experience an immediate financial impact when interest rates rise, while people without mortgages may not experience the same direct increase in their monthly expenses.
This highlights one of the broader challenges of monetary policy: an economy-wide problem can have very different effects on different households.
The RBA’s decisions affect borrowing conditions across the economy, but mortgage holders can feel the impact particularly quickly through their monthly repayments.
RBA Interest Rates and Government Spending
The conversation also moves beyond monetary policy to the relationship between RBA decisions and government spending.
John raises the question of whether government spending can work against efforts to reduce inflation.
The basic economic argument discussed is that government spending can contribute to demand within the economy. If demand remains strong while supply is constrained, there can be continued upward pressure on prices.
At the same time, reducing government spending can have other economic consequences.
The Inflation Versus Economic Growth Challenge
Government policy involves balancing several competing objectives.
Reducing spending could potentially reduce demand and inflationary pressure, but significant cuts could also affect economic activity and employment.
This creates a difficult policy trade-off between controlling inflation and supporting economic growth.
John also discusses the importance of ensuring government spending contributes to productive outcomes, including infrastructure and investment that can improve Australia’s productive capacity.
Why Australia’s Productivity Matters
Productivity is an important part of the broader economic discussion because increasing the economy’s ability to produce goods and services can help support sustainable growth.
The episode contrasts spending on ongoing services with investment in productive infrastructure and other assets.
This does not mean essential services such as healthcare, education or other public programs are unimportant. Rather, the discussion focuses on how governments can balance immediate spending with investments that may contribute to Australia’s longer-term economic capacity.
For households and businesses, productivity matters because a more productive economy can support economic growth without relying solely on increasing demand.
Should the RBA Have Raised Rates Again?
John and Catarina offer different perspectives on the latest decision.
Catarina argues that she would have preferred to keep rates unchanged, particularly given the pressure already being experienced in the housing market and by mortgage holders.
John takes a different approach. He explains that if he were making the decision based on the RBA’s mandate, he would likely support the increase because the central bank’s responsibility is focused on returning inflation towards its target.
The discussion highlights an important distinction between assessing the consequences of a decision and understanding the mandate behind it.
Higher rates can create significant short-term pressure for borrowers, but the RBA’s interest-rate decisions are intended to address broader economic conditions rather than individual household circumstances.
What Should Mortgage Holders Do Now?
Mortgage holders facing higher repayments may need to review their finances carefully.
Potential areas to consider include:
- Reviewing the current mortgage interest rate
- Comparing available refinancing options
- Assessing whether extending the loan term is appropriate
- Reviewing household spending and cash flow
- Maintaining an emergency buffer where possible
- Understanding the long-term cost of refinancing
- Seeking professional advice before making major financial decisions
The right approach will depend on each household’s income, debt, savings, property position and financial objectives.

Frequently Asked Questions About the RBA Rate Hike and Mortgage Holders
What is the RBA cash rate?
The cash rate is the interest rate set by the Reserve Bank of Australia and influences borrowing and lending rates throughout the Australian economy.
How does an RBA rate increase affect mortgages?
Higher cash rates can lead to higher variable mortgage rates, which can increase monthly repayments for borrowers.
Can extending a mortgage term reduce repayments?
Extending a mortgage term can reduce the required monthly repayment, but it may increase the total amount of interest paid over the life of the loan.
Could higher interest rates affect property prices?
Higher borrowing costs can reduce borrowing capacity and demand, which can place downward pressure on property prices. The impact varies between locations and market conditions.
Why does the RBA increase interest rates when inflation is high?
Higher interest rates can reduce borrowing and spending, helping to moderate demand and, over time, reduce inflationary pressure.
Should mortgage holders refinance when rates rise?
Refinancing may be worth considering for some borrowers, but the benefits depend on the available rates, fees, loan term and individual financial circumstances.
Get Professional Accounting and Financial Guidance
If rising interest rates, mortgage costs or broader economic conditions are affecting your business or financial decisions, professional advice can help you understand your options.
Latitude Accountants works with Australian individuals and businesses to provide practical, proactive accounting and advisory support.
Get in touch:
📍 Sydney Olympic Park | Marrickville | Melbourne | Loxton | Adelaide
📞 1300 706 597
📧 info@latitudeaccountants.com.au
Disclaimer
This article is general information and commentary only and does not constitute financial, tax, property, investment or business advice. Individual circumstances vary. Speak with a qualified professional adviser before making financial or investment decisions.
Free Consultation
Got questions after reading this?
Book a call with our team. We'll walk through your situation and help you understand your options — no obligation.
Book Your Free Consultation*Free for all ABN holders · Limited spots available
Call 1300 706 597What We Do
Chartered accountants who work proactively
Not just at tax time — all year round.
Before You Make a Move
Six times you should call us first
Most costly mistakes happen before the paperwork is signed.
Buying a vehicle
Structure, FBT, and depreciation all need to be right before you sign.
Taking money out
Wages, dividends, or drawings each carry different tax consequences.
Buying property
Who buys it changes your GST, land tax, and CGT position entirely.
Hiring your first employee
Payroll, super, and STP obligations kick in from day one.
Buying or selling a business
You can inherit someone else's tax debt. Know what you're buying first.
Taking on a partner
Equity splits need proper structure upfront. A handshake deal costs more to unwind.
Get In Touch
Stop Guessing. Start Making Better Decisions.
Get clarity on your numbers, your structure, and your next move. Speak directly with our team and walk away knowing exactly where you stand.