Guides & Resources
Australian Mortgage Stress Is Rising: Why More Homeowners Are Falling Behind
Mortgage stress is rising across Australia as higher repayments squeeze households.
Discover why homeowners are falling behind and what options remain.

Australian homeowners are facing growing financial pressure as higher interest rates, declining property values and rising household expenses make mortgage repayments increasingly difficult to manage.
For many households, the challenge is no longer simply finding ways to save money. It is maintaining essential living expenses while keeping up with mortgage commitments that have become considerably more expensive.
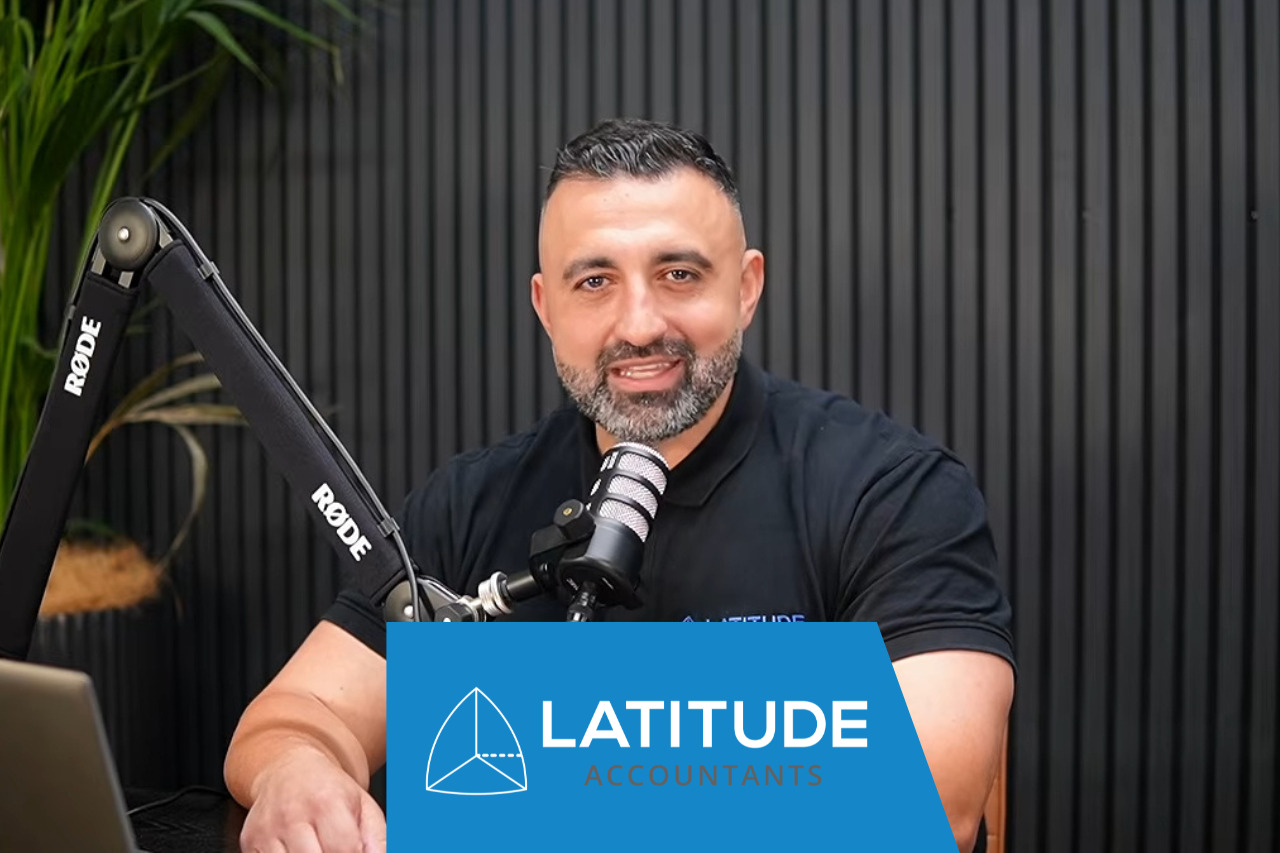
In this episode of The CEO Breakdown, John Saade, CEO of Latitude Accountants, examines Australia’s worsening mortgage stress, highlighting rising mortgage arrears in outer suburban Sydney and Melbourne, the growing risks facing recent property buyers and the potential consequences for the broader Australian economy.
With some mortgage stress hotspots recording arrears well above the national average, understanding what is driving this financial pressure has become increasingly important.
What Is Mortgage Stress in Australia?
Mortgage stress generally describes a situation where housing repayments place significant pressure on a household’s financial position.
A commonly referenced indicator is when mortgage repayments exceed 30% of gross household income. However, this measure does not necessarily reflect every borrower’s circumstances.
A household earning a higher income may comfortably manage repayments above this threshold, while another household may struggle with a smaller mortgage commitment because of essential living expenses or other debts.
More concerning is when mortgage stress develops into mortgage arrears.
Mortgage Stress vs Mortgage Arrears: What’s the Difference?
Although closely related, these terms describe different financial situations.
- Mortgage stress: Difficulty managing mortgage repayments alongside other household expenses.
- Mortgage arrears: Mortgage repayments that have become overdue.
- Negative equity: A situation where the outstanding mortgage exceeds the property’s current market value.
A homeowner can experience mortgage stress without missing repayments. However, prolonged financial pressure may eventually increase the risk of falling into arrears.

Why Are More Australian Homeowners Falling Behind on Mortgage Repayments?
Several economic pressures are contributing to Australia’s mortgage repayment challenges.
1. Higher Interest Rates Are Increasing Repayments
Interest rate increases directly affect households with variable-rate mortgages and borrowers transitioning from previously lower fixed-rate arrangements.
As repayments rise, less disposable income remains available for groceries, utilities, transport, insurance and other essential expenses.
Households that borrowed when interest rates were considerably lower may now find their original budgets are no longer sustainable.
2. Household Expenses Are Squeezing Available Income
Mortgage repayments are only one component of household spending.
Rising everyday expenses can reduce the financial buffer available to meet housing commitments.
Some homeowners may respond by reducing discretionary spending, delaying important purchases or relying on savings to maintain repayments.
However, these adjustments may become increasingly difficult to sustain over time.
3. Recent Property Buyers Have Less Financial Flexibility
Homeowners who entered the property market near its peak may be particularly exposed.
Those who purchased with smaller deposits generally have less initial equity available to absorb declining property values.
When higher repayments coincide with falling house prices, refinancing or selling can become more complicated.
Australia’s Mortgage Stress Hotspots: Where Are Arrears Rising?
Mortgage pressure is not distributed evenly across Australia.
In The CEO Breakdown, John Saade discusses reports identifying outer suburban areas of Sydney and Melbourne as particularly exposed to mortgage repayment difficulties.
The episode highlights several suburbs experiencing elevated mortgage arrears.
|
Suburb |
State |
Reported Mortgage Arrears |
|
Pakenham |
Victoria |
2.88% |
|
Constitution Hill |
New South Wales |
2.42% |
|
Point Cook |
Victoria |
2.40% |
|
Baulkham Hills |
New South Wales |
2.26% |
Figures referenced in The CEO Breakdown reflect the reporting discussed during the episode and should not be interpreted as live mortgage arrears statistics.
These figures highlight how financial pressure can become concentrated in areas where borrowers face significant mortgage commitments relative to their household incomes.
Why Are Outer Suburban Homeowners Particularly Vulnerable?
Outer suburban areas attracted many buyers seeking more affordable housing during periods of strong property market activity.
However, borrowers who purchased with large mortgages during lower interest rate environments may now face substantially higher repayment obligations.
For households with limited savings or slower income growth, this creates additional financial vulnerability.
How Falling Property Prices Can Make Mortgage Stress Worse
Declining property values can compound existing mortgage difficulties.
When homeowners experience repayment pressure, refinancing may appear to offer a solution. However, lenders assess applications against current income, property valuations and borrowing requirements.
If a property’s value has fallen, the homeowner may have less equity available to support refinancing.
In more severe circumstances, they may enter negative equity.
The Risk of Negative Equity for Recent Homebuyers
Consider a hypothetical homeowner who purchases a property for $800,000 with a 5% deposit.
Their initial mortgage would be approximately $760,000, excluding additional purchasing costs.
If the property’s value subsequently declines by 10%, it would be worth approximately $720,000.
Assuming the outstanding loan balance remains unchanged, the homeowner would owe $40,000 more than the property’s market value.
While negative equity does not automatically require someone to sell, it can limit financial flexibility when repayment difficulties arise.
What Happens When Homeowners Can No Longer Afford Their Mortgage?
Persistent mortgage stress can have consequences beyond missed repayments.
Households experiencing prolonged financial difficulties may face:
- Increasing mortgage arrears.
- Reduced savings and emergency funds.
- Greater reliance on personal loans or credit cards.
- Difficulty refinancing existing mortgages.
- Pressure to downsize or sell their property.
- Potential financial hardship arrangements with lenders.
In serious cases, unresolved mortgage arrears may eventually result in enforcement action by lenders.
However, homeowners experiencing financial difficulties should explore available assistance before reaching that stage.
Practical Steps to Manage Rising Mortgage Stress
If mortgage repayments are becoming difficult, early action can help clarify the available options.
Contact your lender early. Discuss your circumstances and enquire about financial hardship assistance or potential repayment arrangements.
Review your household budget. Identify essential expenses, outstanding debts and opportunities to improve available cash flow.
Seek qualified mortgage advice. A licensed mortgage broker may help assess whether refinancing or alternative lending arrangements are appropriate.
Understand your financial position. Accurate income records, expense tracking and realistic financial planning can help support better decisions.
Consider longer-term affordability. If maintaining the property requires ongoing financial sacrifices that are no longer sustainable, reviewing your housing strategy may be necessary.
Could Rising Mortgage Stress Affect Australia’s Broader Economy?
Mortgage stress is not exclusively a household problem.
When homeowners direct more income towards repayments, they generally have less money available for discretionary spending.
Reduced consumer spending can affect retailers, hospitality businesses, service providers and other sectors that rely on household demand.
If financial pressure continues alongside weakening employment conditions, businesses may experience slower revenue growth and additional cash-flow challenges.
This connection between household finances and business performance is particularly important for Australian small business owners.

Frequently Asked Questions About Mortgage Stress in Australia
What is considered mortgage stress in Australia?
Mortgage stress generally occurs when housing repayments place significant pressure on household finances. Spending more than 30% of gross income on repayments is a commonly used indicator, although individual circumstances vary.
What happens if I fall behind on mortgage repayments?
Missed repayments can result in arrears, additional charges and potential impacts on your credit history. Contact your lender as early as possible to discuss available hardship assistance.
Can falling house prices increase mortgage stress?
Yes. Declining property values can reduce available equity and make refinancing or selling more difficult, particularly for homeowners who purchased with smaller deposits.
Can I refinance my home loan while experiencing mortgage stress?
Possibly. Refinancing approval depends on your income, existing debts, property equity and current lending requirements. A qualified mortgage broker can assess available options.
Navigate Financial Uncertainty With Latitude Accountants
Rising mortgage stress highlights the importance of understanding your financial commitments and maintaining a sustainable financial position.
For Australian business owners, household financial pressure can also affect business cash flow, investment decisions and long-term planning.
At Latitude Accountants, our team provides proactive accounting, tax and business advisory services to help business owners understand their financial position, manage obligations and make informed decisions.
Whether you need assistance with cash-flow planning, business structures, tax obligations or investment-related accounting, we’re here to help.
Book a Free Business Discovery Call for ABN Holders.
Contact Latitude Accountants:
📍 Sydney Olympic Park | Marrickville | Melbourne | Loxton | Adelaide
📞 1300 706 597
📧 info@latitudeaccountants.com.au
Disclaimer
This article provides general information only and does not constitute financial, tax, accounting, legal, property, mortgage or business advice. Economic conditions, lending requirements and property market information may change. Readers should seek advice from an appropriately qualified professional regarding their individual circumstances before making financial, borrowing or property-related decisions.
Free Consultation
Got questions after reading this?
Book a call with our team. We'll walk through your situation and help you understand your options — no obligation.
Book Your Free Consultation*Free for all ABN holders · Limited spots available
Call 1300 706 597What We Do
Chartered accountants who work proactively
Not just at tax time — all year round.
Before You Make a Move
Six times you should call us first
Most costly mistakes happen before the paperwork is signed.
Buying a vehicle
Structure, FBT, and depreciation all need to be right before you sign.
Taking money out
Wages, dividends, or drawings each carry different tax consequences.
Buying property
Who buys it changes your GST, land tax, and CGT position entirely.
Hiring your first employee
Payroll, super, and STP obligations kick in from day one.
Buying or selling a business
You can inherit someone else's tax debt. Know what you're buying first.
Taking on a partner
Equity splits need proper structure upfront. A handshake deal costs more to unwind.
Get In Touch
Stop Guessing. Start Making Better Decisions.
Get clarity on your numbers, your structure, and your next move. Speak directly with our team and walk away knowing exactly where you stand.