Guides & Resources
Home Buyers Just Got Squeezed Again. What Happens to Prices Now?
Australia's cash rate hits 4.85%.
Discover how higher interest rates affect home buyers, borrowing capacity and property prices.

Australian home buyers are facing another financial challenge following the Reserve Bank of Australia’s (RBA) decision to raise the cash rate by another 0.25 percentage points to 4.85%. With borrowing costs climbing and everyday expenses continuing to increase, households are finding it harder to secure a property without stretching their finances.
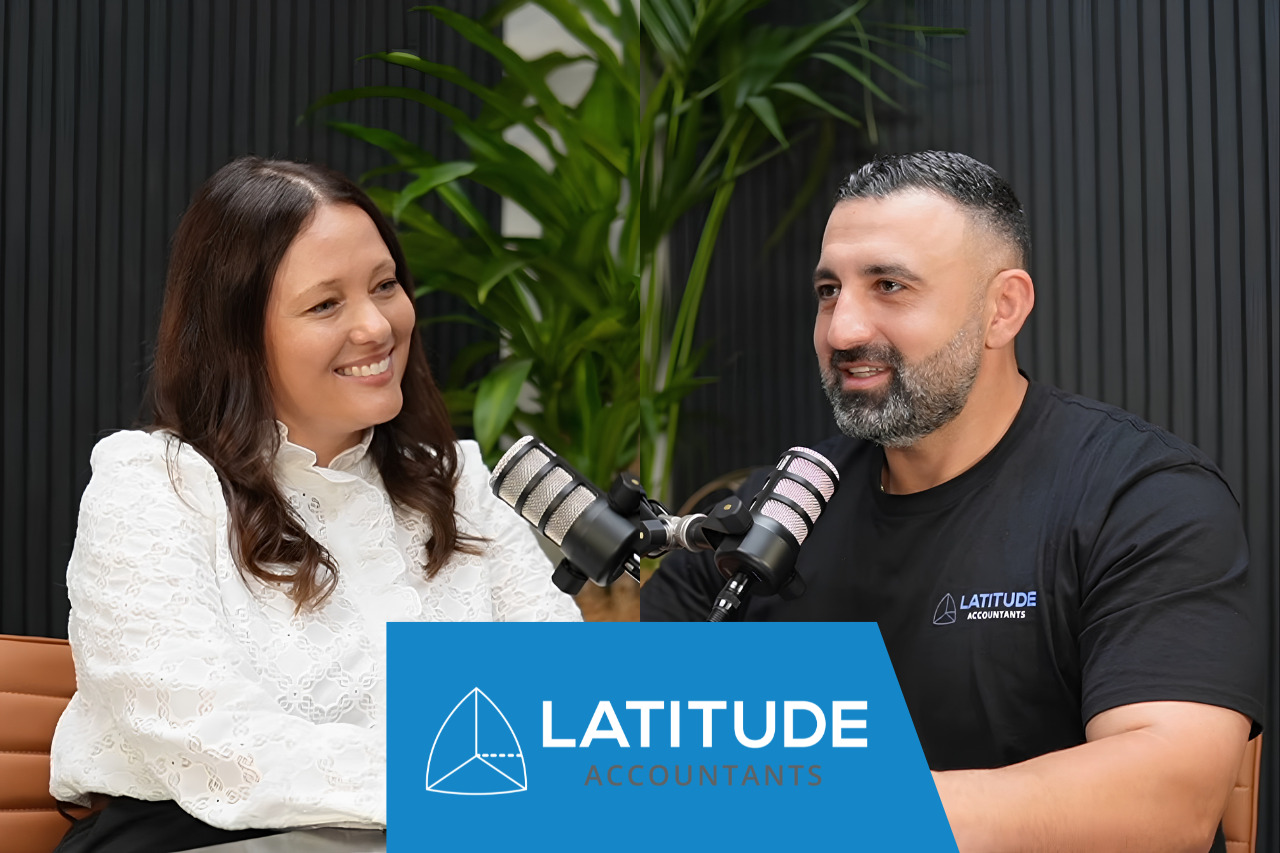
In this episode of The Account Rant, Latitude Accountants CEO John Saade sits down with Karen Wirihana, founder and mortgage broker at Kaleo Finance, to discuss what the latest interest rate increase means for Australian households and the property market.
Their conversation explores the growing pressure on mortgage holders, how banks assess borrowing capacity, why single-income buyers face additional challenges and whether falling property prices could finally give buyers more negotiating power.
For first-home buyers, existing mortgage holders and anyone considering entering the property market, understanding these changes is essential before making a major financial commitment.
RBA Raises Cash Rate to 4.85%: What Does It Mean for Home Buyers?
The RBA’s latest 0.25 percentage point increase takes Australia’s cash rate to 4.85%, its highest level since 2008. It also marks the fifth interest rate increase in 2026, adding further pressure to households already managing higher living costs.
For mortgage holders with variable interest rates, another increase can mean higher monthly repayments. According to the discussion between John Saade and Karen Wirihana, households in New South Wales could face an additional $680 per month in mortgage repayments.
That is a substantial increase for families already dealing with rising grocery bills, fuel costs, school fees and other everyday expenses.
The impact extends beyond existing homeowners. People currently applying for home loans may discover that their borrowing capacity has decreased, potentially affecting the properties they can afford.
For first-home buyers who are already close to their borrowing limits, even a relatively small interest rate increase could be enough to change their purchasing plans.

Why Did the RBA Raise Interest Rates Again?
The primary reason behind the latest rate increase is persistent inflation.
The RBA has indicated that inflation remains elevated, with several factors contributing to the pressure on Australia’s economy.
These include:
- Higher fuel and commodity prices: Middle East tensions have contributed to increased energy and transportation costs, affecting businesses and consumers.
- Rising operating expenses: Businesses face higher costs for supplies, transport and other essential services, which can eventually flow through to consumer prices.
- Domestic capacity constraints: Pressure on Australia’s available resources and productive capacity can contribute to higher prices.
- Technology investment: Increased investment associated with artificial intelligence is also contributing to technology-related price pressures.
The challenge is that higher interest rates are being introduced when many households are already experiencing financial strain.
While monetary policy aims to bring inflation under control, the additional repayment pressure can make it harder for Australians to maintain their savings, manage household expenses and enter the property market.
How Banks Calculate Your Borrowing Capacity
One of the most important points raised by Karen Wirihana is that banks do not always assess borrowing capacity using a household’s actual living expenses.
When reviewing a home loan application, lenders generally consider several factors:
- Household income and employment stability.
- Existing financial commitments and liabilities.
- Credit card limits and personal loans.
- Household living expenses.
- Mortgage repayments under higher assessment interest rates.
However, lenders may apply their own living expense benchmarks, often informed by household expenditure data.
This means someone who carefully manages their money and spends less than the average household benchmark may still be assessed using a higher assumed living expense figure.
For example, a buyer who regularly saves money by keeping grocery, transport and entertainment expenses low might expect those savings to improve their borrowing capacity.
However, if the lender applies a higher benchmark, the buyer may not receive the full benefit of their disciplined spending habits.
This can create frustration for people who have worked hard to save a deposit and demonstrate that they can comfortably manage repayments.
Why Your Actual Spending May Not Match the Bank’s Assessment
Banks use standardised expense assessments to account for the possibility that applicants may temporarily reduce their spending before applying for a mortgage.
Lenders want to ensure borrowers can continue meeting repayments even if their circumstances change.
While this approach provides a level of protection, it can also disadvantage applicants whose actual spending is consistently below the assumed benchmark.
Understanding how lenders calculate these figures can help prospective buyers identify potential borrowing limitations before committing to a property.
Why Single-Income Buyers Face Greater Challenges
The property market can be particularly difficult for Australians relying on a single income.
During the discussion, Karen highlights how lending assessments can favour households with two incomes, making it harder for single buyers to compete, particularly in expensive markets such as Sydney.
This is especially challenging for women rebuilding their finances after separation or divorce, including single mothers supporting children.
Moving from a two-income household to a single-income household can significantly change someone’s borrowing capacity, even when they have maintained responsible financial habits.
Other challenges can include:
- Second jobs: Additional employment income may not always be fully recognised by lenders.
- Overtime payments: Some lenders may assess overtime using a lower or averaged figure rather than the full amount earned.
- Child support: Irregular payments may be discounted or treated cautiously when calculating income.
- Dependants: Children still contribute to household expenses, which can reduce the amount a lender is prepared to approve.
These considerations can make it considerably harder for single-income buyers to secure a mortgage, even when they have stable employment and a genuine ability to manage repayments.
How the Help to Buy Scheme Could Support Eligible Buyers
The federal Help to Buy scheme was another important topic discussed by John Saade and Karen Wirihana.
The scheme allows eligible buyers to purchase a property with government assistance through a shared equity arrangement.
Under the arrangement discussed in the episode, the government may contribute up to 30% towards an existing home or 40% towards a new home, subject to eligibility requirements and scheme conditions.
This can reduce the amount a buyer needs to borrow and potentially make home ownership more accessible.
However, Karen also highlights some practical challenges, including the limited number of participating lenders and the additional processing involved in these applications.
For single parents and women rebuilding their financial position after separation, the scheme may provide an opportunity to return to the property market.
It is important to understand the eligibility criteria, participating lenders, property price caps and ongoing obligations before relying on the scheme as part of a purchasing strategy.
Falling Property Prices Could Give Buyers More Negotiating Power
Despite the challenges created by higher interest rates, there may be an opportunity emerging for buyers.
Karen points out that changing market conditions are giving some purchasers something they have struggled to obtain for years: negotiating power.
When properties remain on the market for longer, sellers may become more willing to consider lower offers, particularly when they are motivated to complete a sale.
For buyers with an approved loan and a suitable deposit, this could create opportunities to negotiate a more affordable purchase price.
However, lower property prices do not automatically make buying affordable. Higher interest rates can offset some of the savings from purchasing at a lower price.
Buyers should consider:
- Long-term affordability: Make sure repayments remain manageable even if interest rates increase further.
- Negotiating opportunities: Research comparable sales and use market conditions to support your offer.
- Borrowing limits: Understand your actual borrowing capacity before making commitments.
- Long-term ownership: Consider whether the property suits your needs over the next five to ten years.
- Financial buffers: Maintain savings for unexpected expenses, repairs and changes in household income.
A property purchase should be based on financial readiness rather than fear of missing out or speculation about where prices will move next.
What Should Australian Home Buyers Do Next?
The latest interest rate increase reinforces the importance of understanding your financial position before entering the property market.
Whether you are purchasing your first home, refinancing an existing mortgage or rebuilding your finances after a major life change, preparation can make a significant difference.
Start by reviewing your household budget, existing liabilities and available savings. Understand how lenders assess your income and expenses, and consider whether your repayments would remain manageable under different interest rate scenarios.
It is also worth speaking with a qualified mortgage broker about available lending options, particularly if you have additional income sources, dependants or circumstances that may affect a standard loan application.
For business owners, managing cash flow, personal income and tax obligations is equally important, particularly when personal borrowing capacity depends on business financial performance.
Ultimately, a changing property market can create opportunities, but those opportunities are most valuable when supported by sound financial planning.

Frequently Asked Questions About Interest Rates and Australian Property Prices
Will higher interest rates cause Australian property prices to fall?
Higher interest rates can reduce borrowing capacity and buyer demand, potentially putting downward pressure on property prices. However, prices also depend on housing supply, employment, population growth and local market conditions.
How does an RBA rate increase affect mortgage repayments?
When lenders pass on an interest rate increase, borrowers with variable-rate mortgages may face higher repayments. The actual increase depends on the outstanding loan balance, interest rate and remaining loan term.
Why do banks use living expense benchmarks?
Lenders use household expenditure benchmarks to assess whether applicants can reasonably afford loan repayments. These figures help account for potential changes in spending and provide a consistent assessment approach.
Can single parents qualify for a home loan?
Yes. Single parents can qualify for home loans if they meet a lender’s income, expense, credit and borrowing requirements. However, child support, additional income and dependant-related expenses may affect how lenders assess applications.
What is the Help to Buy scheme in Australia?
The Help to Buy scheme is a federal shared equity initiative that allows eligible buyers to purchase a home with a government contribution towards the property price. Eligibility conditions, property limits and participating lender requirements apply.
Is now a good time to buy property in Australia?
There is no universal answer. Buyers with stable finances, sufficient savings and manageable repayments may find opportunities in a market where sellers are more open to negotiation. However, individual financial circumstances and long-term affordability should guide the decision.
Speak With Latitude Accountants About Your Financial Position
Navigating higher interest rates, rising household expenses and changing property market conditions requires careful financial planning.
At Latitude Accountants, we help Australian individuals and business owners understand their financial position, manage tax obligations and make informed decisions that support their long-term goals.
Whether you need assistance with tax planning, business accounting or understanding your financial position, our team is here to help.
Accounting Done Right. The Latitude Way.
📍 Sydney Olympic Park | Marrickville | Melbourne | Loxton
📞 Phone: 1300 706 597
📧 Email: info@latitudeaccountants.com.au
Disclaimer
This article is general information only and does not constitute financial, tax, accounting, legal, mortgage or property advice. Interest rate decisions, lending policies and government scheme requirements may change. Individual circumstances vary, and readers should seek advice from appropriately qualified financial, mortgage, tax or legal professionals before making financial or property-related decisions.
Free Consultation
Got questions after reading this?
Book a call with our team. We'll walk through your situation and help you understand your options — no obligation.
Book Your Free Consultation*Free for all ABN holders · Limited spots available
Call 1300 706 597What We Do
Chartered accountants who work proactively
Not just at tax time — all year round.
Before You Make a Move
Six times you should call us first
Most costly mistakes happen before the paperwork is signed.
Buying a vehicle
Structure, FBT, and depreciation all need to be right before you sign.
Taking money out
Wages, dividends, or drawings each carry different tax consequences.
Buying property
Who buys it changes your GST, land tax, and CGT position entirely.
Hiring your first employee
Payroll, super, and STP obligations kick in from day one.
Buying or selling a business
You can inherit someone else's tax debt. Know what you're buying first.
Taking on a partner
Equity splits need proper structure upfront. A handshake deal costs more to unwind.
Get In Touch
Stop Guessing. Start Making Better Decisions.
Get clarity on your numbers, your structure, and your next move. Speak directly with our team and walk away knowing exactly where you stand.