Guides & Resources
Keegan Hipgrave: What Happens When Your NRL Career Ends?
Keegan Hipgrave shares lessons on NRL money, investing, early retirement,
And finding purpose after professional sport with Jacob Fahmy.
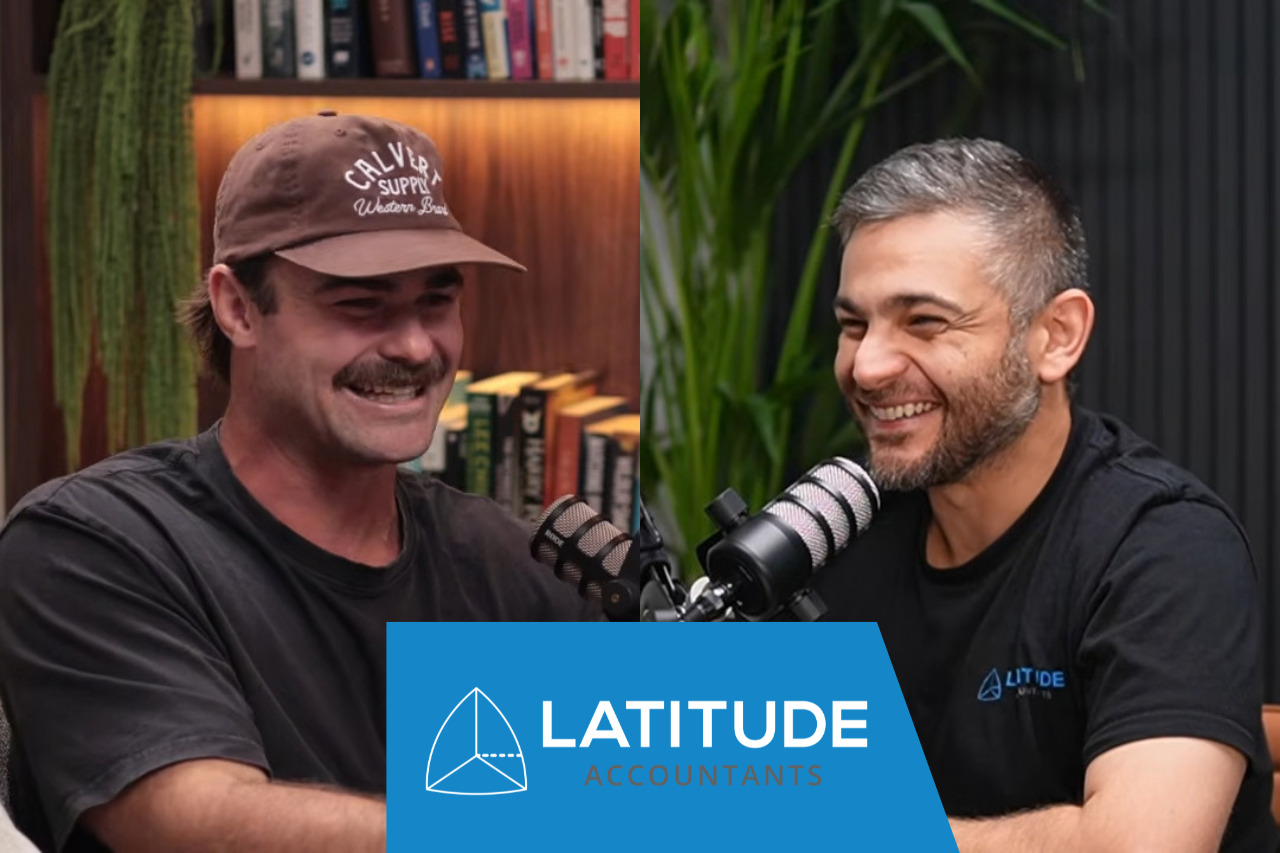

Professional sport can provide incredible opportunities, but a career in the NRL can also change very quickly. For Keegan Hipgrave, that meant signing his first professional contract as a teenager, buying his first property at 20 and building plans around a long playing career — only to be medically retired at 24.
In a conversation with Latitude Accountants’ Jacob Fahmy on The Lat Chat, Keegan opened up about money, saving, property, professional sport and the difficult transition that comes when the career you have built your identity around suddenly ends.
His story offers useful lessons for anyone earning a high income at a young age, particularly when that income may not last forever.
Starting a Professional Career at 17
Keegan signed his first professional contract with the Brisbane Broncos at just 17. From a hardworking family, he said his initial financial goal was simple: to earn enough to cover everyday expenses like fuel and groceries.
His first professional contract changed that situation dramatically.
Rather than treating the increased income as an opportunity to increase his lifestyle immediately, Keegan focused on saving. His parents had already taught him some basic money habits, and he developed a personal goal of buying a house before turning 20.
That goal became a major influence on his early financial decisions.

Buying His First Property at 20
Keegan ultimately bought his first house at 20 while still with the Broncos. At the same age, he also achieved his goal of making his NRL debut.
He described himself as being particularly frugal during those early years. Instead of spending heavily on lifestyle expenses, he prioritised saving towards his property goal.
Looking back, Keegan acknowledged that part of the motivation may have been youthful ambition, but the decisions had a lasting impact on his financial position.
He told Jacob that those early decisions helped set him up for what came later in his career.
Why Early Financial Decisions Matter
For young professionals who suddenly experience a significant increase in income, Keegan’s experience highlights several important considerations:
- Avoid automatically increasing lifestyle spending when income rises.
- Set specific financial goals rather than simply saving without a purpose.
- Build savings before committing to unnecessary expenses.
- Consider how long your current income is likely to last.
- Seek appropriate financial and professional guidance when making major decisions.
The key lesson is not that every young athlete should buy property. Instead, it is that having a clear financial plan can help turn a temporary period of high income into longer-term financial stability.
The Challenge of Managing Money as a Young Athlete
Keegan also reflected on what can happen when young players suddenly receive large amounts of money.
He recalled seeing players receive their first contracts and spend the money without building savings, investments or property. As he explained to Jacob, receiving significant amounts of money at 18, 19 or 20 can be difficult to manage without the right guidance and support.
Professional sporting organisations can provide education around investing and other life skills. However, Keegan emphasised that ultimately, the individual has to decide whether they will act on that information.
This is particularly relevant for athletes because professional sporting careers can be relatively short and unpredictable.
A high income today does not necessarily mean the same income will be available in five, 10 or 20 years.
Building Financial Security Before Your Career Ends
Keegan spent eight years within the NRL system, including time with the Brisbane Broncos, Gold Coast Titans and Parramatta Eels.
He originally expected to have a much longer playing career. His plans included continuing into his 30s and potentially playing overseas.
Instead, repeated concussions brought his playing career to an unexpected end at just 24.
That experience demonstrates why financial planning should not only focus on current income. It should also consider what happens if circumstances change earlier than expected.
For professionals in sport, business or physically demanding industries, this can mean thinking about:
- Emergency savings and accessible cash reserves
- Existing debts and mortgage commitments
- Long-term investments
- Career transition plans
- Skills and education outside the current career
- The financial impact of an unexpected loss of income
What Happens When an NRL Career Suddenly Ends?
Keegan described his medical retirement as a shock. He had another year remaining on his contract and suddenly had to consider what would come next.
The financial questions were significant. At the time, he had two mortgages and had to think about what his future income would look like.
But the transition was about much more than money.
Keegan explained that retirement can affect several parts of a person’s life at once, including their career, finances, sense of purpose, training routine and social community.
After retirement, he worked with the Rugby League Players’ Association, helping other players transition out of the NRL. Through that experience, he saw that people struggled with the transition in different ways.
Some missed the community and connection of being around teammates. Others struggled with the financial changes or the psychological side of leaving professional sport.
Finding a New Purpose After Professional Sport
Keegan’s own transition did not happen overnight.
He initially worked for a disability support service before moving into the RLPA. He eventually became interested in psychology and began the Keegan and Company podcast, where he speaks with athletes about their struggles and challenges.
The process took several years.
Rather than immediately trying to recreate his NRL career in another field, Keegan described the transition as climbing back down the mountain before beginning the climb up another one.
The skills developed during professional sport — including discipline, hard work, resilience and recognising opportunities — could then be applied to his next career.
Career Transition Is More Than Finding Another Job
Keegan’s story demonstrates that career transition can involve more than replacing one source of income with another.
For someone leaving a highly structured professional environment, it may also involve rebuilding:
- A daily routine
- Professional identity
- Social connections
- Financial plans
- Long-term goals
- A sense of purpose
Taking time to work out what comes next can be an important part of the process.
The Role of Financial Planning During Career Transitions
Keegan also discussed selling his first property after retirement because he was uncertain about what his future income would look like. He wanted more capital available in the bank while navigating the transition.
In his circumstances, he viewed that decision as a practical way to create greater flexibility during an uncertain period.
There is no single financial strategy that works for everyone. The right approach depends on income, debt, assets, expenses, goals and individual circumstances.
What Keegan’s experience reinforces is the importance of having enough financial flexibility to make decisions when circumstances change.
Planning for a Career That May Not Last Forever
Professional athletes are not the only people who can benefit from this way of thinking.
Business owners, contractors, tradespeople and professionals can also experience sudden changes in income or career direction.
A strong financial foundation can provide more options when unexpected events occur.
That might involve maintaining appropriate cash reserves, managing debt carefully, diversifying income sources or developing skills that can support a future career.
The goal is not to predict exactly what will happen. It is to avoid being completely unprepared if something does.
What Keegan Hipgrave’s Story Teaches About Money and Career
Keegan’s journey from a 17-year-old professional player to early retirement and a new career highlights several broader lessons:
- High income can create opportunity, but it also requires discipline.
- Financial goals can help control lifestyle spending.
- A career can end earlier than expected.
- Financial security is about more than earning a high income.
- Career transitions can affect identity, routine and purpose as well as finances.
- Having flexibility can make unexpected changes easier to navigate.
- The skills developed in one career can be valuable in another.
For Keegan, retirement eventually became something he viewed positively because it allowed him to pursue work he now finds deeply meaningful.
His experience is a reminder that financial planning is not simply about preparing for retirement at the traditional retirement age. It can also be about preparing for the unexpected transitions that happen throughout life.

Frequently Asked Questions About Life After Professional Sport and Financial Planning
How can young athletes manage a sudden increase in income?
Young athletes can start by establishing clear financial goals, controlling lifestyle inflation, building savings and seeking appropriate professional advice. The aim is to turn a period of high income into a stronger long-term financial foundation.
Why is financial planning important for professional athletes?
Professional sporting careers can be relatively short and may end unexpectedly because of injury, performance changes or other circumstances. Financial planning can help athletes prepare for life after their playing career.
What should athletes consider before retirement?
Athletes may need to consider their savings, investments, debt, future income, career options, education and personal goals. It can also be useful to prepare for the lifestyle and identity changes that can come with leaving professional sport.
What can happen financially when a career ends unexpectedly?
An unexpected career change can create pressure around existing debts, mortgages, household expenses and future income. Having accessible savings and a broader financial plan can provide greater flexibility during the transition.
Can an accountant help with financial planning during a career transition?
An accountant can help assess your financial position, understand tax considerations and structure your finances around your changing circumstances. For more complex financial planning needs, other qualified professionals may also be appropriate.
Talk to Latitude Accountants
Whether you’re a professional athlete, business owner or individual experiencing a major career change, having a clear understanding of your finances can help you make informed decisions about what’s next.
Latitude Accountants provides tax, accounting and advisory services designed to help Australians make better financial and business decisions.
📍 Sydney Olympic Park | Marrickville | Melbourne | Loxton | Adelaide
📞 1300 706 597
📧 info@latitudeaccountants.com.au
Get in touch with Latitude Accountants to discuss your accounting needs.
Disclaimer
This article is provided for general information only and does not constitute financial, tax, accounting, legal or business advice. Individual circumstances vary, and you should speak with a qualified professional before making financial or investment decisions.
Free Consultation
Got questions after reading this?
Book a call with our team. We'll walk through your situation and help you understand your options — no obligation.
Book Your Free Consultation*Free for all ABN holders · Limited spots available
Call 1300 706 597What We Do
Chartered accountants who work proactively
Not just at tax time — all year round.
Before You Make a Move
Six times you should call us first
Most costly mistakes happen before the paperwork is signed.
Buying a vehicle
Structure, FBT, and depreciation all need to be right before you sign.
Taking money out
Wages, dividends, or drawings each carry different tax consequences.
Buying property
Who buys it changes your GST, land tax, and CGT position entirely.
Hiring your first employee
Payroll, super, and STP obligations kick in from day one.
Buying or selling a business
You can inherit someone else's tax debt. Know what you're buying first.
Taking on a partner
Equity splits need proper structure upfront. A handshake deal costs more to unwind.
Get In Touch
Stop Guessing. Start Making Better Decisions.
Get clarity on your numbers, your structure, and your next move. Speak directly with our team and walk away knowing exactly where you stand.