Guides & Resources
Can You Liquidate a Company and Start Again?
Thinking about liquidation?
Learn what happens next, when starting a new business is possible, and how directors can avoid phoenix activity.

When a company becomes insolvent, liquidation can feel like the end of the road for a business owner. But does going into liquidation really mean you can never own or operate a business again?
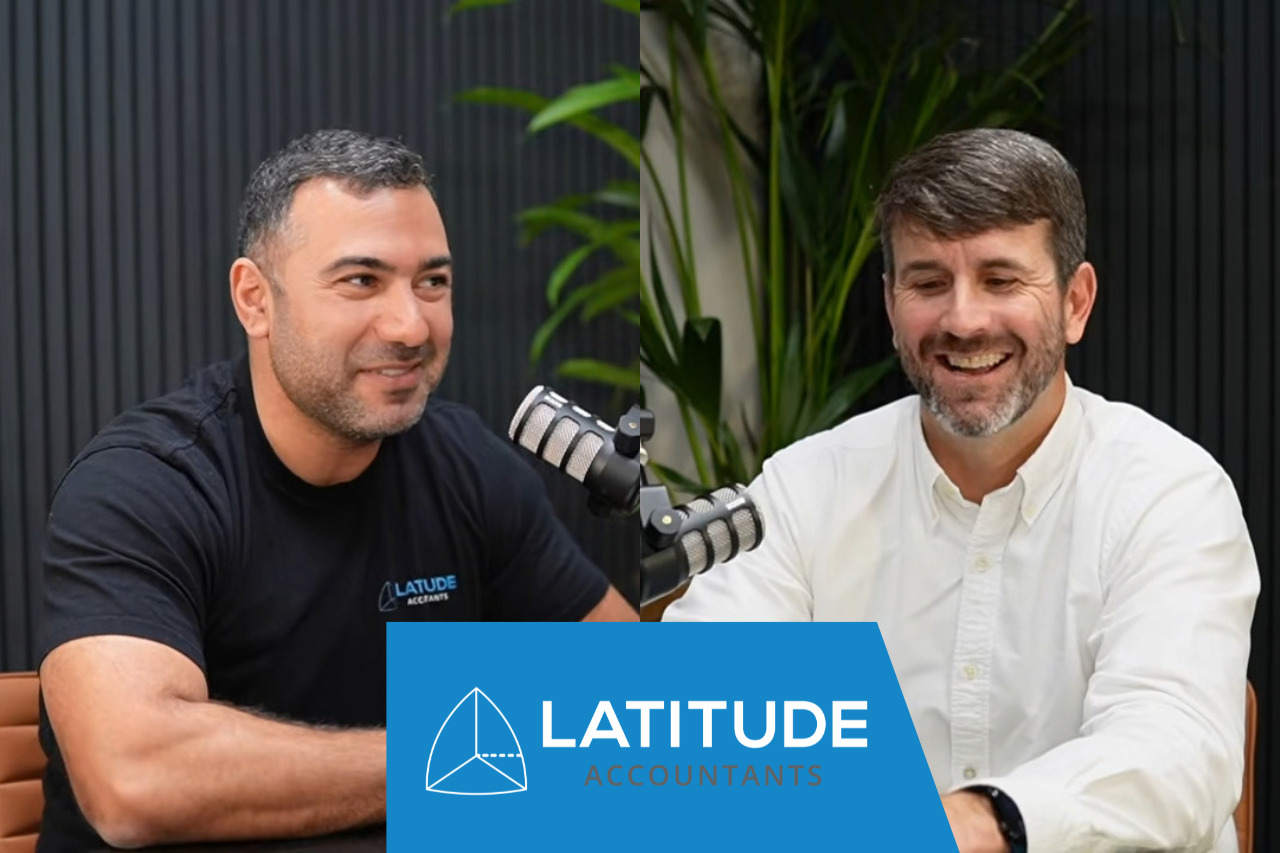
In this episode of The Account Rant, Toufic Haddad of Latitude Accountants sits down with David Ingram from I&R Advisory to unpack the reality of starting again after company liquidation.
Together, they discuss when a business owner can legitimately start a new company, what happens to the old company’s assets and customers, and where the line is drawn between a genuine fresh start and illegal phoenix activity.
As David explains, the key issue isn’t simply whether a director starts another business. It’s how the new business is established and whether assets, contracts, customers or other business value have been improperly transferred away from the old company and its creditors.
What Happens When a Company Goes Into Liquidation?
Liquidation is a formal process for winding up a company and dealing with its assets and liabilities.
For some business owners, liquidation may be the appropriate course of action when a company is no longer viable. A business can fail for many reasons, including cash flow problems, poor management, changing market conditions or circumstances outside the director’s control.
A legitimate business failure does not automatically mean the director can never work in business again.
However, directors still have responsibilities throughout the process. Attempts to remove or transfer company assets for less than their proper value can create serious problems.
As discussed by Toufic and David, examples can include:
- Selling company assets to a family member below market value
- Transferring a business for substantially less than it is worth
- Moving company money into a director’s personal bank account
- Transferring customers or contracts without proper consideration
- Hiding assets from a liquidator
- Moving business value into another entity before liquidation
These actions can potentially be investigated and recovered through the liquidation process.

What Is Phoenix Activity?
Phoenix activity generally refers to a situation where an insolvent company transfers its business to another entity, allowing it to continue while leaving debts and creditors behind.
Not every business restart following liquidation is illegal.
The concern arises when business value is moved from the old company to another party or entity for little or inadequate consideration, particularly where creditors are left unpaid.
David gives the example of a business potentially worth hundreds of thousands of dollars being sold sideways to another party for a nominal amount.
The value may include much more than physical assets. It can also involve:
- Business goodwill
- Customer relationships
- Existing contracts
- Future bookings
- Trading operations
- Plant and equipment
- Other valuable business assets
Where assets or business value are transferred improperly, a liquidator may investigate the transaction and seek to recover value for creditors.
What About Selling Assets to Family Members?
Selling assets to a related party does not automatically make a transaction illegal.
The circumstances and value of the transaction matter.
For example, David describes a situation involving a pub that had been sold to a family member for substantially less than its assessed value. After the liquidators investigated the transaction, they pursued recovery of the asset and ultimately resold it at market value.
The important lesson is that transferring an asset to someone you know does not remove the company’s obligations to its creditors.
Can You Liquidate a Company and Start Again?
Yes, according to the discussion between Toufic and David, a director can potentially start a new business after their previous company has entered liquidation.
But the new business must genuinely be a fresh start.
David explains that there is nothing inherently unlawful about a director establishing another company after liquidation. The problem arises when the director simply transfers the old company’s assets, contracts, customers or business value into the new entity without properly accounting for that value.
For example, a business owner might legitimately:
- Place an insolvent company into liquidation
- Establish a new company
- Purchase new equipment
- Purchase assets from the liquidator at an appropriate market value
- Build a new customer base and trading operation
- Continue operating in the same industry
The fact that the director previously operated a failed company does not, by itself, prevent them from having another opportunity.
A Real Example of Starting Again Properly
Toufic and David discuss a real example involving a photographer whose company had become insolvent.
The business owned valuable photography equipment, and the owner was concerned that liquidation would mean he could never work in the industry again.
Instead, the old company was liquidated and the equipment was purchased from the liquidator at market value. The director was then able to establish a new business and continue trading.
The distinction was important: the assets were not secretly transferred away from creditors. They were dealt with through the liquidation process and purchased at an appropriate value.
The business owner was subsequently able to trade profitably again.
This demonstrates that business failure and misconduct are not necessarily the same thing.
A failed business does not have to define a person’s entire business career.
What Makes Starting Again Potentially Illegal?
The situation changes when a director deliberately attempts to strip value from the old company before liquidation.
For example, the discussion highlights conduct such as:
- Concealing company assets from a liquidator
- Claiming assets have been lost when they have not
- Moving future bookings to a new company
- Redirecting customers to another entity
- Issuing new-company invoices for work belonging to the old company
- Transferring assets for substantially less than their value
- Moving company funds into personal accounts
These actions can potentially undermine the interests of creditors and may result in recovery action or regulatory consequences.
The difference is therefore not simply old company versus new company. It is whether the new business has been established legitimately and whether the old company’s assets and value have been properly dealt with.
What Happens to Directors Who Transfer Assets?
Liquidators have duties to investigate the company’s affairs and transactions.
Where potentially improper transactions are identified, they can take steps to recover money or assets that should properly be available to the company and its creditors.
Liquidators also have reporting obligations to the Australian Securities and Investments Commission (ASIC) in relation to certain transactions and conduct.
Depending on the circumstances, consequences can involve civil recovery action or other regulatory and legal consequences.
This is why attempting to move assets or business value shortly before liquidation can create significantly greater problems than dealing with insolvency openly and properly.
Can You Pay Old Suppliers After Starting a New Business?
Starting a legitimate new business does not necessarily prevent a former director from voluntarily paying old suppliers from the new business.
Toufic and David discuss how a director may wish to make good on some old debts, particularly where they have longstanding relationships with suppliers.
However, the new business still needs to operate as a legitimate entity, and suppliers may choose to change their trading arrangements, such as requiring cash on delivery to protect their position.
Can ASIC Ban a Director After Liquidation?
A company entering liquidation does not automatically mean a director will be banned from acting as a director.
According to the discussion, ASIC can take action depending on the circumstances, particularly where there are serious breaches of relevant laws or other misconduct.
David explains that there are circumstances where ASIC can disqualify a director for a period of up to five years, including situations involving multiple failed entities. However, the circumstances surrounding the failures and the director’s conduct are important considerations.
The broader point is that business failure alone is not necessarily misconduct.
The Difference Between Business Failure and Misconduct
One of the most important takeaways from the conversation is that directors should not assume liquidation automatically ends their career.
Businesses can fail. What matters is how the director responds to that failure.
A legitimate restart involves dealing honestly with the old company’s assets and creditors and establishing the new business properly.
By contrast, deliberately moving assets, customers, contracts or money away from the old company to avoid creditors can expose a director to serious consequences.
If your company is experiencing financial difficulty, getting professional advice early can help you understand your options before the situation becomes more complicated.

Frequently Asked Questions About Liquidating a Company and Starting Again
Can I start a new company after my old company goes into liquidation?
Potentially, yes. Liquidation does not automatically prevent a director from establishing another business. However, the new business needs to be established legitimately and should not improperly receive assets, contracts, customers or other value belonging to the old company.
Is starting another company after liquidation automatically phoenix activity?
No. A genuine new business following a legitimate liquidation is not automatically illegal phoenix activity. The key issue is whether value from the old company has been improperly transferred to the new business.
Can I buy my old company’s assets after liquidation?
Potentially. The discussion provides an example where a former business owner purchased assets from the liquidator at market value and legitimately restarted the business. The specific circumstances and transaction should be properly assessed.
Can I continue working in the same industry after liquidation?
Potentially, yes. A failed company does not automatically prevent its former director from establishing another business or continuing to work in the same industry. However, the new business must be operated separately and lawfully.
What happens if I transfer company assets to a family member before liquidation?
A transfer to a family member may be investigated, particularly if assets were transferred below market value or otherwise for inadequate consideration. A liquidator may seek to recover value for creditors.
Should I move assets or customers to a new company before liquidation?
Directors should not attempt to move company assets, customers, contracts or business value simply to keep them away from creditors. If your company is in financial difficulty, seek professional advice before taking action.
Can a director be banned after a company becomes insolvent?
Potentially, depending on the circumstances and the director’s conduct. Insolvency itself does not automatically mean a director will be banned, but serious breaches or misconduct can result in regulatory action.
Get Advice Before Making Decisions About an Insolvent Company
If your company is experiencing financial difficulty, don’t wait until the situation becomes more complicated.
At Latitude Accountants, we help business owners understand their financial position, obligations and available options so they can make informed decisions about their business.
Get in touch with Latitude Accountants:
📍 Sydney Olympic Park | Marrickville | Melbourne | Loxton | Adelaide
📞 1300 706 597
📧 info@latitudeaccountants.com.au
Book a free business discovery call and speak with our team about your circumstances.
Disclaimer
This article is general information only and does not constitute financial, legal, tax, insolvency or business advice. Every company’s circumstances are different. If your company is experiencing financial difficulty or considering liquidation, speak with a qualified accountant, insolvency practitioner or other appropriate professional adviser before taking action.
Free Consultation
Got questions after reading this?
Book a call with our team. We'll walk through your situation and help you understand your options — no obligation.
Book Your Free Consultation*Free for all ABN holders · Limited spots available
Call 1300 706 597What We Do
Chartered accountants who work proactively
Not just at tax time — all year round.
Before You Make a Move
Six times you should call us first
Most costly mistakes happen before the paperwork is signed.
Buying a vehicle
Structure, FBT, and depreciation all need to be right before you sign.
Taking money out
Wages, dividends, or drawings each carry different tax consequences.
Buying property
Who buys it changes your GST, land tax, and CGT position entirely.
Hiring your first employee
Payroll, super, and STP obligations kick in from day one.
Buying or selling a business
You can inherit someone else's tax debt. Know what you're buying first.
Taking on a partner
Equity splits need proper structure upfront. A handshake deal costs more to unwind.
Get In Touch
Stop Guessing. Start Making Better Decisions.
Get clarity on your numbers, your structure, and your next move. Speak directly with our team and walk away knowing exactly where you stand.