Guides & Resources
Australian Property Market 2026: Are Sydney and Melbourne Leading a Bigger Housing Downturn?
Are Sydney and Melbourne leading Australia's housing downturn?
Explore falling house prices, slowing property sales and what the market shift means in 2026.

Australia’s property market faces growing uncertainty as falling house prices, weakening buyer demand, and declining transaction volumes put pressure on some of the country’s largest housing markets.
Sydney and Melbourne are attracting particular attention, with reports of declining property values and fewer listings raising questions about whether the current slowdown could develop into a broader national housing downturn.
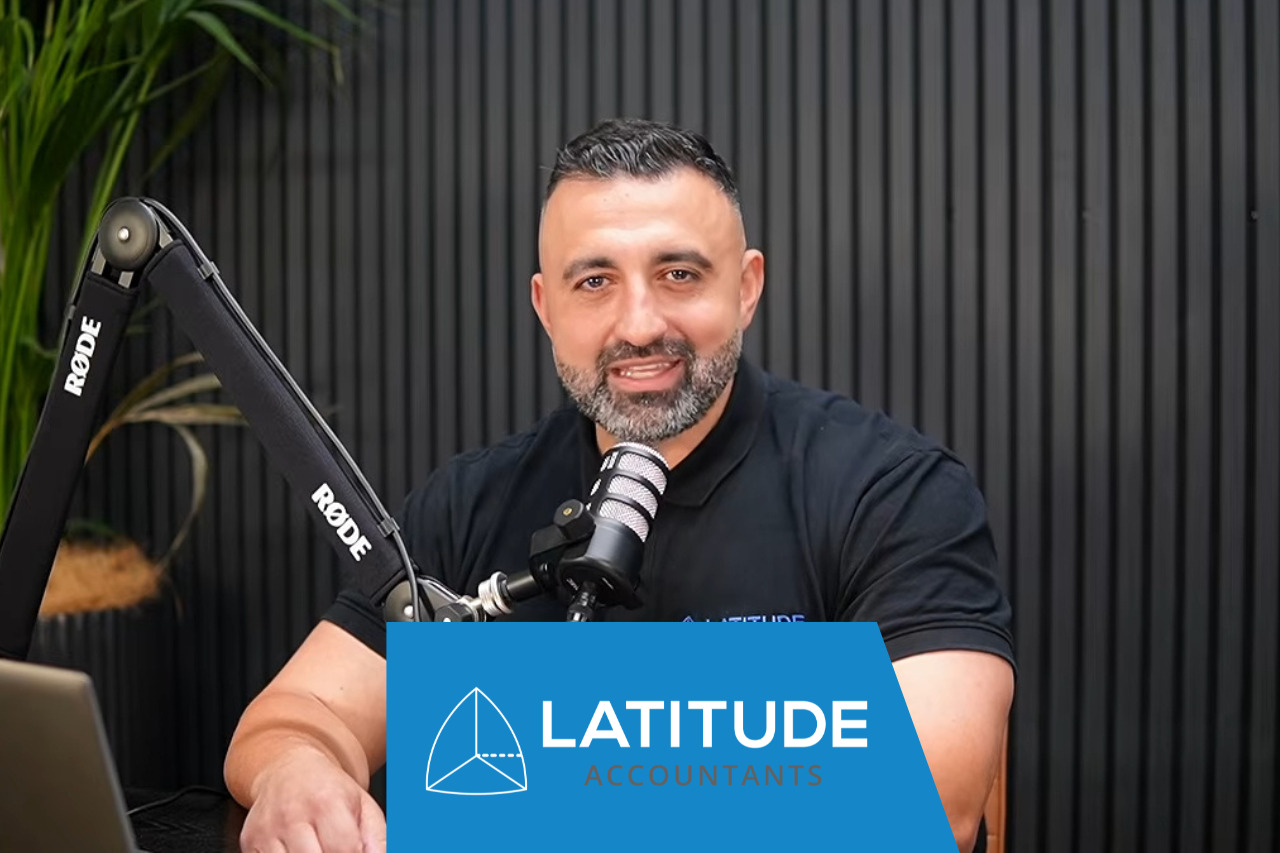
In this episode of The CEO Breakdown, John Saade, CEO of Latitude Accountants, examines Australia’s changing property landscape, highlighting the growing divide between major capital cities, rising mortgage stress and the financial challenges facing homeowners and property investors.
As interest rates, borrowing capacity, and household affordability continue to shape market activity, understanding the forces behind Australia’s property downturn is increasingly important.
Australian Property Market 2026: What Is Happening to House Prices?
Australia’s housing market is experiencing a period of adjustment following years of strong property price growth.
In The CEO Breakdown, John Saade discusses reports indicating that national dwelling values had declined approximately 5% from their March peak, with Sydney and Melbourne recording larger falls.
The figures referenced in the episode include:
|
Property Market |
Reported Price Decline |
|
National dwelling values |
5.0% |
|
Sydney |
7.1% |
|
Melbourne |
6.5% |
These figures reflect market reporting discussed during the episode and are not live property price statistics.
While property performance varies considerably between individual suburbs, the reported declines highlight the pressure facing homeowners who purchased near previous market highs.
Why Are Sydney and Melbourne Experiencing Property Price Falls?
Several factors are contributing to weaker housing market conditions.
These include:
- Higher mortgage repayments reducing borrowing capacity.
- Rising household living expenses.
- Reduced investor demand.
- Increasing mortgage stress among existing homeowners.
- Greater uncertainty surrounding future interest rate movements.
- Buyers becoming more cautious about property prices.
Together, these conditions can reduce the number of people willing or able to purchase property at previous market valuations.

Why Are Property Listings Falling in Sydney and Melbourne?
One of the more interesting developments discussed in The CEO Breakdown involves the decline in property listings across Australia’s two largest capital cities.
According to REA Group figures referenced in the episode, Sydney and Melbourne listings fell approximately 16% during the September quarter compared with the corresponding period a year earlier.
Meanwhile, Brisbane, Perth and Adelaide recorded a combined increase of approximately 17%.
Are Homeowners Choosing Not to Sell?
John Saade suggests that some homeowners in Sydney and Melbourne may be withdrawing properties from the market rather than accepting lower selling prices.
This can create a situation where both property listings and completed transactions decline.
However, fewer listings do not necessarily indicate stronger housing demand.
When buyers are also withdrawing from the market, reduced transaction activity may reflect broader uncertainty rather than improving conditions.
Could Brisbane, Perth and Adelaide Follow Sydney and Melbourne?
While Sydney and Melbourne have attracted considerable attention, other Australian capital cities are not necessarily immune to changing market conditions.
In the episode, John raises concerns that Brisbane, Perth and Adelaide could experience additional pressure as higher interest rates and weaker buyer demand continue affecting borrowing decisions.
These markets previously benefited from strong property price growth, but rising listings may create additional competition between sellers.
Australia’s Emerging Two-Speed Property Market
The contrasting listing trends highlight differences between capital cities.
Sydney and Melbourne have experienced declining listings, while Brisbane, Perth and Adelaide have recorded increased selling activity in the reporting period discussed.
However, property markets operate differently across suburbs, price brackets and dwelling types.
A national housing downturn does not necessarily mean every location will experience identical price movements.
How Mortgage Stress Could Make Australia’s Housing Downturn Worse
Rising mortgage stress is another important factor influencing Australia’s property market.
Higher interest rates increase repayments for variable-rate borrowers, reducing the income available for other household expenses.
Some homeowners may also struggle to refinance because their income no longer satisfies current lending assessments.
When financial pressure becomes unsustainable, selling may become a necessary consideration.
The Growing Risk of Negative Equity
Negative equity occurs when an outstanding mortgage exceeds the property’s current market value.
This risk is particularly relevant for buyers who entered the market with smaller deposits.
For example, a homeowner purchasing a $900,000 property with a 5% deposit would initially borrow approximately $855,000, excluding purchasing costs.
If the property’s value subsequently declined by 10%, it would be worth approximately $810,000.
Assuming the mortgage balance remained unchanged, the homeowner would face approximately $45,000 in negative equity.
This can make refinancing or selling considerably more complicated.
What Does Falling Property Activity Mean for Australian Businesses?
A property downturn affects more than homeowners and investors.
Reduced transaction volumes can also place pressure on businesses that rely on property sales and related services.
Industries potentially affected include:
- Real estate agencies and property sales professionals.
- Mortgage brokers and lending specialists.
- Conveyancers and property lawyers.
- Builders, tradespeople and renovation businesses.
- Property valuers and auctioneers.
- Removalists and other property-related service providers.
When fewer properties change hands, these businesses may experience reduced revenue while continuing to meet wages, rent and operating expenses.
For small business owners, maintaining healthy cash flow and reviewing financial forecasts becomes increasingly important during periods of weaker market activity.
Will Australian House Prices Continue Falling in 2026?
Predicting the exact direction or timing of property prices remains difficult.
John Saade discusses the possibility of a larger peak-to-trough decline, but this represents a market outlook rather than a guaranteed outcome.
Future housing conditions will depend on several interconnected factors, including interest rates, employment, household income, housing supply and buyer confidence.
Rather than attempting to predict the precise bottom of the market, homeowners and investors should focus on affordability, financial sustainability and their individual circumstances.

Frequently Asked Questions About the Australian Property Market in 2026
Are Sydney and Melbourne house prices falling in 2026?
The market reports discussed in The CEO Breakdown identified declining dwelling values across both cities. However, performance varies between suburbs and property types.
Could Australia’s property downturn spread to other capital cities?
It is possible. Higher borrowing costs and weaker buyer demand can affect multiple markets, although the extent of any downturn will depend on local conditions.
Does falling property activity affect small businesses?
Yes. Businesses connected to property transactions may experience reduced demand, lower revenue and additional cash-flow pressure when fewer properties are bought and sold.
Should property investors sell during a housing downturn?
Selling depends on individual financial circumstances, borrowing commitments, investment objectives and potential tax implications. Professional advice is recommended before making significant property decisions.
Plan Ahead With Latitude Accountants
Australia’s changing property market highlights the importance of understanding your financial position before making major investment or business decisions.
At Latitude Accountants, we help Australian business owners and property investors navigate financial uncertainty through proactive accounting, tax planning and business advisory services.
Whether you’re reviewing investment property cash flow, considering capital gains tax implications or preparing your business for changing economic conditions, our experienced team can help you make informed financial decisions.
Book a Free Business Discovery Call for ABN Holders.
Contact Latitude Accountants:
📍 Sydney Olympic Park | Marrickville | Melbourne | Loxton | Adelaide
📞 1300 706 597
📧 info@latitudeaccountants.com.au
Disclaimer
This article provides general information only and does not constitute financial, tax, accounting, legal, property, mortgage or business advice. Property market figures and economic forecasts referenced are based on information discussed in The CEO Breakdown and may change over time. Readers should seek advice from an appropriately qualified professional before making property, investment or financial decisions.
Free Consultation
Got questions after reading this?
Book a call with our team. We'll walk through your situation and help you understand your options — no obligation.
Book Your Free Consultation*Free for all ABN holders · Limited spots available
Call 1300 706 597What We Do
Chartered accountants who work proactively
Not just at tax time — all year round.
Before You Make a Move
Six times you should call us first
Most costly mistakes happen before the paperwork is signed.
Buying a vehicle
Structure, FBT, and depreciation all need to be right before you sign.
Taking money out
Wages, dividends, or drawings each carry different tax consequences.
Buying property
Who buys it changes your GST, land tax, and CGT position entirely.
Hiring your first employee
Payroll, super, and STP obligations kick in from day one.
Buying or selling a business
You can inherit someone else's tax debt. Know what you're buying first.
Taking on a partner
Equity splits need proper structure upfront. A handshake deal costs more to unwind.
Get In Touch
Stop Guessing. Start Making Better Decisions.
Get clarity on your numbers, your structure, and your next move. Speak directly with our team and walk away knowing exactly where you stand.