Guides & Resources
Rentvesting vs Buying a Home: Which Is Better Right Now?
Is rentvesting still worthwhile in Australia?
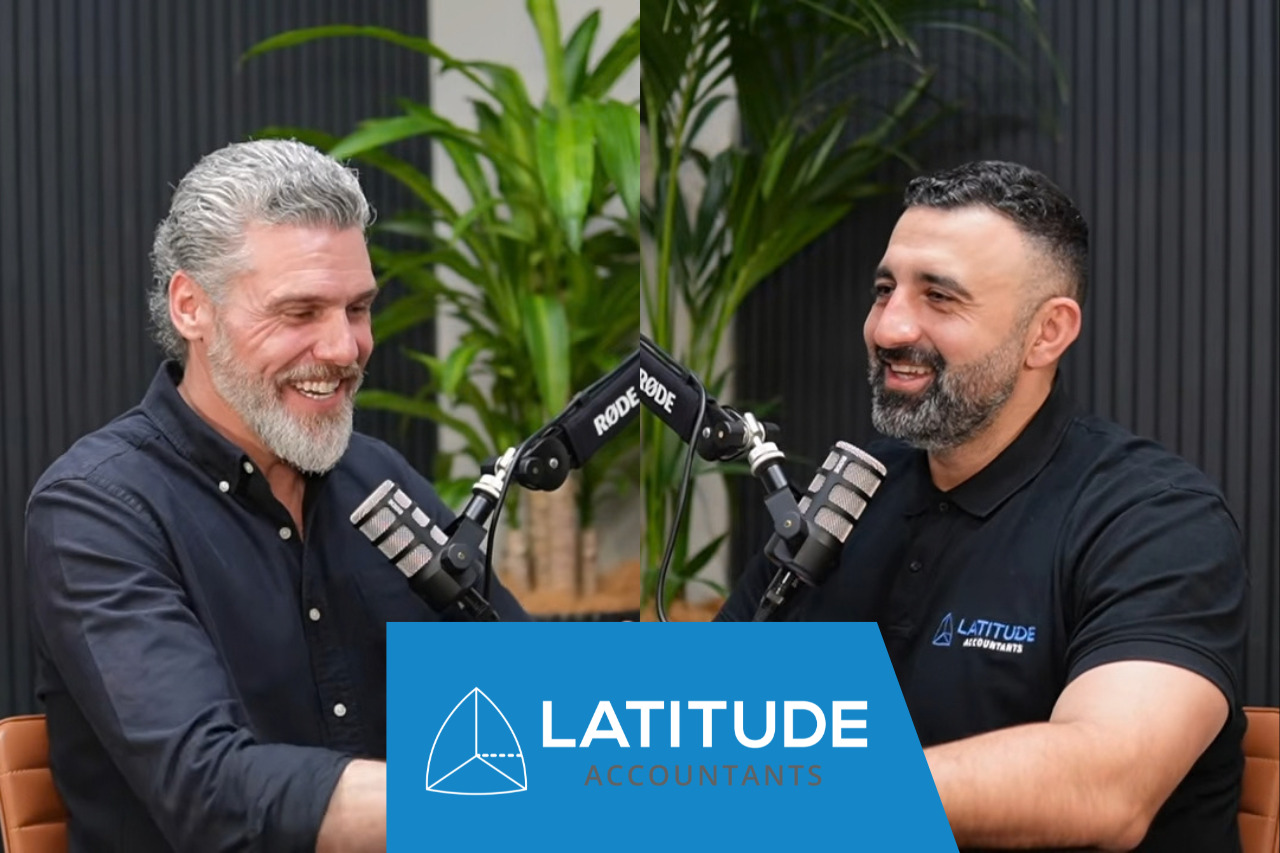
John Saade and Leigh Morris discuss property investing, tax, cash flow, and changing market sentiment.

Rentvesting has become an increasingly discussed strategy for Australians who want to live where they choose while building wealth through property elsewhere. But with property prices, interest rates, tax considerations, and investor sentiment changing, is rentvesting still a strategy worth considering?
In this episode of The Account Rant, John Saade sits down with Leigh Morris, Senior Mortgage Broker and Director at SFP Financial, to discuss whether rentvesting still makes sense in the current property environment.
Leigh has personally used the rentvesting strategy for years, renting his family home while owning investment properties. However, he explains that recent changes to the investment landscape have made him reconsider what comes next.
The conversation explores rentvesting versus buying a home, investment property cash flow, negative gearing, capital gains tax, first-home buyers, superannuation, overseas property and the much-discussed 18.6-year property cycle.
What Is Rentvesting?
Rentvesting involves renting the home you want to live in while purchasing investment properties elsewhere.
Rather than buying a home based purely on where you want to live, a rentvestor can potentially:
- Rent in a preferred location.
- Purchase investment properties in other areas.
- Build equity through property ownership.
- Maintain greater lifestyle flexibility.
- Potentially use investment property tax deductions and capital growth as part of a broader investment strategy.
For Leigh, the strategy has primarily been about flexibility. He explains that his family prefers the convenience of renting an apartment in an area with access to parks, schools, restaurants and other facilities, rather than owning a large home that comes with additional maintenance and costs.

Why Has Rentvesting Worked for Leigh Morris?
Leigh’s approach has not simply involved buying properties and collecting rent. He discusses developing properties, including projects involving a granny flat and a duplex, with the aim of building equity and adding housing supply.
He also highlights several potential advantages of continuing to rent his own home:
Lifestyle flexibility
Renting can make it easier to change locations as circumstances change. For Leigh’s family, this includes the ability to spend time overseas and potentially move between different locations.
Potentially lower lifestyle costs
Buying an owner-occupied property in an expensive area can require a substantial mortgage. Renting may allow someone to live in a preferred location without committing the same amount of capital to their principal residence.
Investment flexibility
Instead of directing all available capital towards an expensive owner-occupied property, a rentvestor may choose to invest elsewhere.
However, these benefits need to be considered alongside the costs, risks and tax implications of owning investment property.
The Main Residence Exemption: A Key Consideration
One of the major issues raised in the discussion is the main residence exemption for capital gains tax (CGT).
Generally, an Australian’s main residence can receive an exemption from CGT when it is sold, subject to the relevant rules and circumstances.
This creates an important consideration for people deciding between buying their own home and continuing to rent.
As John and Leigh discuss, the potential tax-free capital growth of an owner-occupied property can be significant. However, purchasing a home can also involve a large mortgage, interest costs, maintenance and other ownership expenses.
The discussion also touches on the six-year rule, which can allow certain former main residences to continue receiving the main residence CGT exemption for a period after the owner moves out, subject to eligibility and specific circumstances.
Because CGT treatment depends heavily on individual circumstances, property owners should obtain professional tax advice before relying on these rules.
Has Property Investing Become Less Attractive?
A major theme of the conversation is changing investor sentiment.
Leigh explains that he has traditionally been proactive about considering his next property investment. However, he says he is currently taking a more cautious approach because of uncertainty around future property growth, cash flow and changes to the investment environment.
One of the calculations discussed involves the relationship between:
- Property growth
- Inflation
- Interest costs
- Property running expenses
- Rental income
- Tax benefits
For example, Leigh uses a hypothetical $1 million property to illustrate how running costs and negative cash flow can reduce the benefit of capital growth. His broader point is that investors need to look beyond headline property price growth and consider the overall return after costs.
Negative Gearing and Investment Property Cash Flow
Negative gearing is another major part of the discussion.
For an investment property, the income and deductible expenses can result in a taxable loss in certain circumstances. That loss may have tax consequences for the investor, subject to Australian tax rules.
However, a tax deduction does not automatically make an investment profitable.
Investors should consider:
- Rental income
- Interest expenses
- Property management fees
- Maintenance
- Insurance
- Council rates
- Land tax where applicable
- Vacancy periods
- Financing costs
- Potential capital growth
- Tax implications when the property is eventually sold
The transcript highlights how investors are increasingly questioning whether the traditional property investment model still provides an attractive overall proposition.
Why Falling Property Prices May Not Bring First-Home Buyers Back Immediately
It might seem logical that falling property prices would automatically encourage first-home buyers to enter the market.
John and Leigh discuss why that may not necessarily happen.
When the media is dominated by negative property news, potential buyers may become more cautious. Instead of seeing falling prices as an opportunity, they may worry that prices could fall further.
This can create a situation where buyers continue to wait for greater certainty.
The discussion also highlights the potential risks for highly leveraged buyers. Someone purchasing with a relatively small deposit could face significant equity pressure if property values subsequently decline.
For buyers considering property, the key issue is therefore not simply whether prices are rising or falling. Borrowing capacity, cash flow, employment stability, deposit size, location and long-term plans can all affect the suitability of a purchase.
Should Australians Use Superannuation to Buy a Home?
Another topic discussed is whether Australians should have greater access to their superannuation to purchase a home.
Leigh argues that superannuation serves an important purpose as a long-term retirement safety net. John similarly explains that he prefers to keep his super invested in shares as a way of maintaining diversification, given his existing exposure to property.
The conversation also raises an important financial literacy issue.
Using retirement savings for a property purchase may provide an immediate benefit, but it can also reduce the amount available for retirement later.
This is why decisions involving superannuation need to be considered within a person’s broader financial position rather than in isolation.
Is the 18.6-Year Property Cycle Predicting a Major Correction?
Towards the end of the episode, John and Leigh put their “tinfoil hats” on to discuss the 18.6-year property cycle.
The theory suggests that property markets may experience recurring long-term cycles, with major downturns potentially occurring around an 18-year timeframe.
Leigh expresses scepticism about the idea, pointing out that economic conditions can change dramatically over such a long period.
The discussion references 2027 and 2028 as dates sometimes associated with the theory, but neither John nor Leigh presents the cycle as a reliable forecasting tool. Instead, the exchange is deliberately framed as speculative and humorous.
For property investors, this is an important distinction: historical patterns and market theories can be interesting to examine, but they do not eliminate the uncertainty involved in forecasting future property prices.
What Should Property Investors Consider?
The conversation between John Saade and Leigh Morris highlights that there is no single property strategy that will suit every Australian.
Whether someone chooses to rentvest, buy their own home or invest through another asset class depends on their circumstances and objectives.
Before making a property decision, consider:
- Your current income and borrowing capacity.
- Your expected holding period.
- Investment property cash flow.
- Interest rate exposure.
- Potential capital growth.
- Tax implications.
- CGT considerations.
- Land tax and ownership costs.
- Your lifestyle priorities.
- Diversification across different asset classes.
- Your retirement strategy.
- Your tolerance for investment risk.
Most importantly, property should not be assessed purely on whether prices are currently rising or falling.
The real question is whether the strategy makes sense for your financial position, objectives and timeframe.

Frequently Asked Questions About Life After Professional Sport and Financial Planning
How can young athletes manage a sudden increase in income?
Young athletes can start by establishing clear financial goals, controlling lifestyle inflation, building savings and seeking appropriate professional advice. The aim is to turn a period of high income into a stronger long-term financial foundation.
Why is financial planning important for professional athletes?
Professional sporting careers can be relatively short and may end unexpectedly because of injury, performance changes or other circumstances. Financial planning can help athletes prepare for life after their playing career.
What should athletes consider before retirement?
Athletes may need to consider their savings, investments, debt, future income, career options, education and personal goals. It can also be useful to prepare for the lifestyle and identity changes that can come with leaving professional sport.
What can happen financially when a career ends unexpectedly?
An unexpected career change can create pressure around existing debts, mortgages, household expenses and future income. Having accessible savings and a broader financial plan can provide greater flexibility during the transition.
Can an accountant help with financial planning during a career transition?
An accountant can help assess your financial position, understand tax considerations and structure your finances around your changing circumstances. For more complex financial planning needs, other qualified professionals may also be appropriate.
Talk to Latitude Accountants
Whether you’re a professional athlete, business owner or individual experiencing a major career change, having a clear understanding of your finances can help you make informed decisions about what’s next.
Latitude Accountants provides tax, accounting and advisory services designed to help Australians make better financial and business decisions.
📍 Sydney Olympic Park | Marrickville | Melbourne | Loxton | Adelaide
📞 1300 706 597
📧 info@latitudeaccountants.com.au
Get in touch with Latitude Accountants to discuss your accounting needs.
Disclaimer
This article is provided for general information only and does not constitute financial, tax, accounting, legal or business advice. Individual circumstances vary, and you should speak with a qualified professional before making financial or investment decisions.
Free Consultation
Got questions after reading this?
Book a call with our team. We'll walk through your situation and help you understand your options — no obligation.
Book Your Free Consultation*Free for all ABN holders · Limited spots available
Call 1300 706 597What We Do
Chartered accountants who work proactively
Not just at tax time — all year round.
Before You Make a Move
Six times you should call us first
Most costly mistakes happen before the paperwork is signed.
Buying a vehicle
Structure, FBT, and depreciation all need to be right before you sign.
Taking money out
Wages, dividends, or drawings each carry different tax consequences.
Buying property
Who buys it changes your GST, land tax, and CGT position entirely.
Hiring your first employee
Payroll, super, and STP obligations kick in from day one.
Buying or selling a business
You can inherit someone else's tax debt. Know what you're buying first.
Taking on a partner
Equity splits need proper structure upfront. A handshake deal costs more to unwind.
Get In Touch
Stop Guessing. Start Making Better Decisions.
Get clarity on your numbers, your structure, and your next move. Speak directly with our team and walk away knowing exactly where you stand.