Guides & Resources
How to Actually Make Money as a Tradie: Budgeting, Pricing and Cash Flow
Learn how to make money as a tradie with smarter budgeting, pricing and cash flow management.
Understand your costs, set targets and grow your business.

Being booked out for months doesn’t necessarily mean your trade business is making money. You might have invoices going out every week, plenty of jobs lined up and a steady stream of customers, yet still struggle to cover wages, materials, tax and other business expenses.
So, where does all the money go?
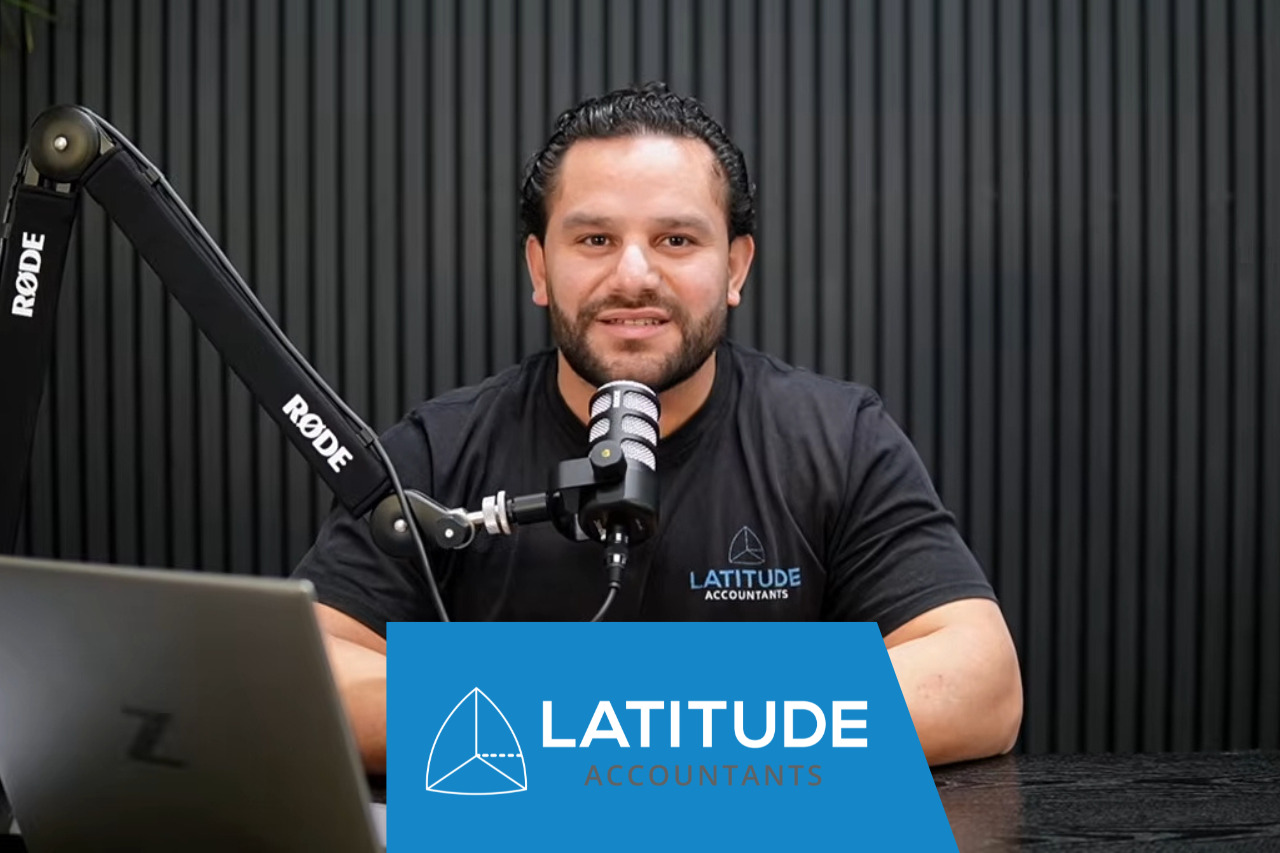
In this episode of Tradie Pat, Pat from Latitude Accountants breaks down budgeting and cash flow for Australian tradies, explaining how to calculate your operating expenses, determine what you should charge and set realistic sales targets.
Whether you’re a sole operator or preparing to hire your first apprentice, understanding your numbers is essential to building a profitable trade business.
Why Profit and Cash Flow Are Different for Tradies
One of the biggest financial mistakes tradies make is assuming that a profitable business automatically has money available in the bank.
Profit represents what remains after accounting for business income and expenses. Cash flow tracks the actual money entering and leaving your business.
For example, you might complete a $15,000 job and issue an invoice, but if the customer takes 30 days to pay, you still need enough cash to cover your immediate expenses.
This is why every trade business needs both a realistic budget and a cash flow forecast.

Step 1: Calculate How Much Your Trade Business Costs to Run
Before setting your sales targets, determine how much money your business needs to survive.
Pat recommends starting with operating expenses rather than estimating revenue first. This approach allows you to establish clear weekly and monthly billing targets based on actual business costs.
Start With Your Own Wage
Your personal living expenses should determine how much you need to pay yourself.
For example, if you need $1,000 per week in take-home pay, your business must account for more than simply withdrawing $52,000 annually.
Depending on your business structure, additional employment costs may include:
- Gross wages and PAYG withholding.
- Employer superannuation contributions.
- Workers’ compensation insurance, where applicable.
- Other relevant employment obligations.
In Pat’s example, approximately $1,204 in weekly gross wages provides $1,000 in take-home pay, based on the assumptions used.
Your actual figures will depend on your circumstances and applicable tax rates.
Identify Your Operating Expenses
Many tradies underestimate the smaller costs associated with running their businesses.
Your budget should consider:
- Public liability and other business insurance.
- Vehicle fuel, registration, insurance and servicing.
- Accounting and bookkeeping fees.
- Accounting software and business subscriptions.
- Telephone and internet expenses.
- Tools, equipment, maintenance and replacements.
- Advertising and marketing.
- ASIC fees, where applicable.
- Uniforms and office supplies.
- Unexpected or miscellaneous expenses.
Pat also recommends allowing approximately $500 per month for miscellaneous operating expenses in his example.
Having this buffer helps protect your business when unexpected costs arise.
Step 2: Understand Your Break-Even Point
Your break-even point is the amount of gross profit your business needs to generate to cover its operating expenses without making a loss.
In Pat’s example, a basic trade business paying its owner a wage requires approximately $130,000 in annual gross profit to break even.
However, breaking even shouldn’t be your ultimate business goal.
If you want to generate an additional $20,000 in annual net profit, your gross profit target increases to approximately $150,000.
This gives you a clearer financial objective when quoting jobs and planning your workload.
Step 3: Work Out How Much You Should Charge Per Hour
One common mistake tradies make is calculating their hourly rate based on a standard 40-hour working week.
In reality, not every working hour is billable.
You also spend time preparing quotes, purchasing materials, travelling between jobs, handling paperwork and communicating with customers.
Pat uses the following example:
|
Calculation |
Amount |
|
Billable hours per week |
30 hours |
|
Working weeks annually |
48 weeks |
|
Total annual billable hours |
1,440 hours |
|
Annual gross profit target |
$150,000 |
|
Required hourly rate |
$104.17 |
Based on these assumptions, you would need to charge approximately $104 per billable hour to achieve your target from your own labour.
Your actual rate should reflect your trade, overheads, market conditions and desired profit margin.
Step 4: Don’t Forget to Mark Up Your Materials
Your labour isn’t the only opportunity to generate profit.
Materials require ordering, collection, transportation, handling and administration. These activities consume valuable business resources.
Pat explains that many tradies apply a markup of approximately 10% to materials.
However, the appropriate markup depends on your costs, contractual arrangements and pricing strategy.
For budgeting purposes, Pat also demonstrates a scenario where materials represent approximately 30% of total sales.
Accounting for material costs properly helps ensure your business generates enough gross profit to cover operating expenses.
Step 5: Set Realistic Monthly Sales Targets
Once you’ve calculated your expenses and desired profit, you can establish a monthly sales target.
Using Pat’s simplified example:
- Annual gross profit target: $150,000.
- Monthly gross profit target: $12,500.
- Assumed materials and direct costs: 30% of sales.
- Required monthly sales: approximately $17,857.
This means your business needs to generate approximately $214,286 in annual revenue under these assumptions.
Your actual sales target will change depending on your material costs, subcontractor expenses and other direct job costs.
The important thing is to establish measurable targets rather than relying on how busy your calendar looks.
Step 6: Budget Before Hiring an Apprentice
Hiring an apprentice can help increase your business capacity, but it also introduces additional expenses.
Before employing someone, account for their wages, superannuation, workers’ compensation, training commitments, leave entitlements and other employment obligations.
Pat demonstrates how adding an apprentice can increase the required monthly sales target to approximately $26,190, based on his revised budget assumptions.
He also explains that an apprentice may have fewer billable hours because of training and other commitments.
Always check current minimum pay rates and employment obligations through the Fair Work Ombudsman before finalising your budget.

Frequently Asked Questions About Tradie Budgeting and Cash Flow
How much should a tradie charge per hour?
Your hourly rate should cover operating expenses, wages and your desired profit. Pat’s example calculates approximately $104 per billable hour, although actual rates vary between businesses.
Why is my trade business profitable but has no cash?
Outstanding invoices, tax obligations, equipment purchases and loan repayments can reduce available cash even when your accounts show a profit.
Should tradies mark up materials?
A reasonable materials markup can help recover purchasing, handling and administration costs. Your pricing should reflect your actual expenses and agreed customer terms.
How often should I review my business budget?
Review your budget monthly and update it whenever high costs, staffing arrangements or sales expectations change.
Get Your Trade Business Finances Sorted With Latitude Accountants
Running a successful trade business takes more than winning jobs. You need accurate financial information, realistic pricing and a clear understanding of where your money goes.
At Latitude Accountants, we help Australian business owners understand their numbers, manage their financial obligations and make informed decisions about business growth.
Whether you’re starting your trade business, reviewing your pricing or preparing to hire employees, our team can help.
Get a free consultation for ABN holders.
📍 Sydney Olympic Park | Marrickville | Melbourne | Loxton | Adelaide
📞 1300 706 597
📧 info@latitudeaccountants.com.au.
Disclaimer
This content is general information only and does not constitute financial, tax, accounting, legal, property or business advice. Figures presented are illustrative and based on assumptions discussed in the episode. Actual costs, tax obligations, employment requirements and profitability will vary. Speak with a qualified adviser about your individual circumstances.
Free Consultation
Got questions after reading this?
Book a call with our team. We'll walk through your situation and help you understand your options — no obligation.
Book Your Free Consultation*Free for all ABN holders · Limited spots available
Call 1300 706 597What We Do
Chartered accountants who work proactively
Not just at tax time — all year round.
Before You Make a Move
Six times you should call us first
Most costly mistakes happen before the paperwork is signed.
Buying a vehicle
Structure, FBT, and depreciation all need to be right before you sign.
Taking money out
Wages, dividends, or drawings each carry different tax consequences.
Buying property
Who buys it changes your GST, land tax, and CGT position entirely.
Hiring your first employee
Payroll, super, and STP obligations kick in from day one.
Buying or selling a business
You can inherit someone else's tax debt. Know what you're buying first.
Taking on a partner
Equity splits need proper structure upfront. A handshake deal costs more to unwind.
Get In Touch
Stop Guessing. Start Making Better Decisions.
Get clarity on your numbers, your structure, and your next move. Speak directly with our team and walk away knowing exactly where you stand.