Guides & Resources
Accountants React to ASIC’s 10 Budgeting Tips: Do They Actually Work?
Latitude Accountants reviews 10 popular money-saving strategies
And reveals which ones are worth trying.

Budgeting sounds simple on paper. Track your expenses, save regularly, cut unnecessary spending and stick to your financial goals. But when mortgage repayments increase, unexpected bills arrive and everyday living costs continue to climb, following a strict budget becomes much harder.
So, how practical is the budgeting advice Australians receive?
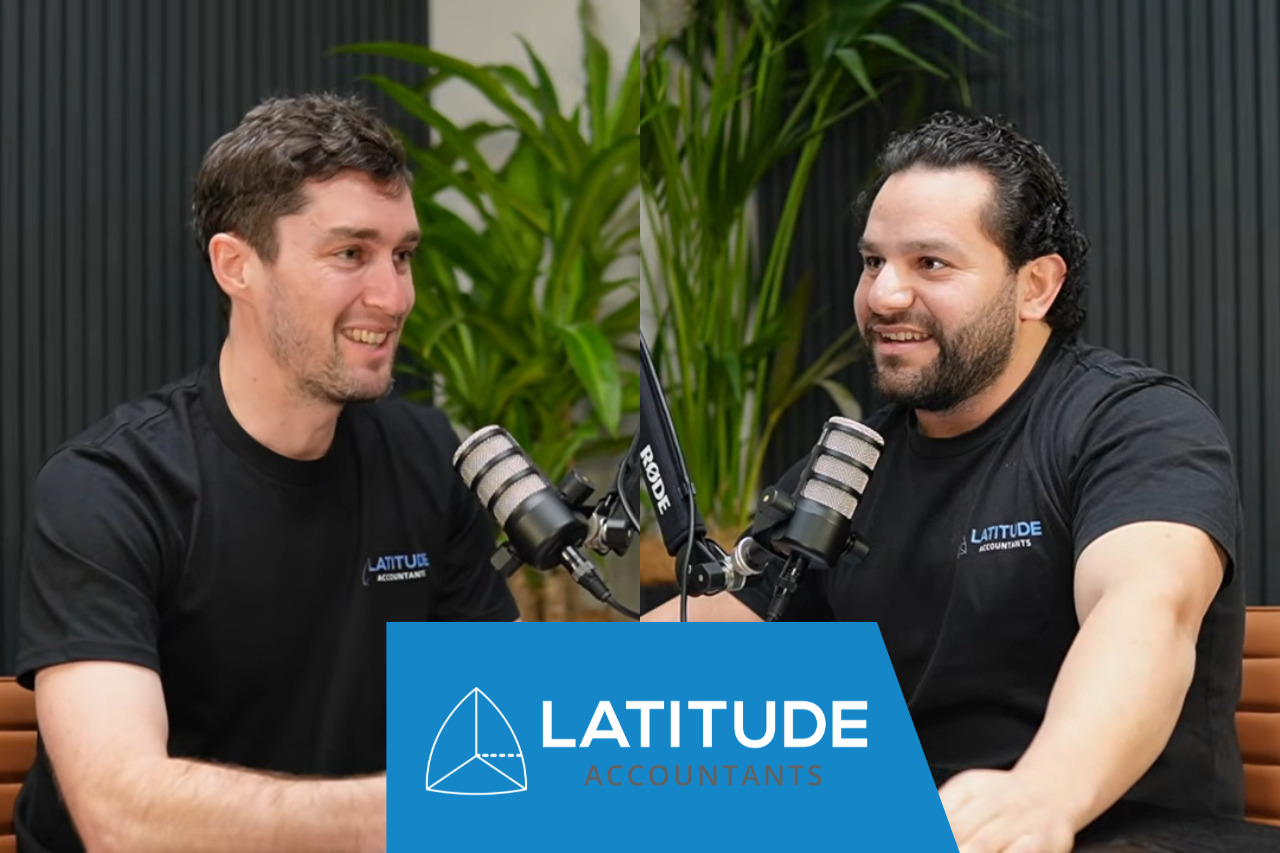
In this episode of The Account Rant, Latitude Accountants’ Patrick El-Bitar and James Lamb review 10 budgeting tips from ASIC MoneySmart, discussing which strategies genuinely help Australians manage their money and which might need a more flexible approach.
From offset accounts and automatic savings to subscription creep and weekly spending limits, here’s what they had to say.

1. Track Every Dollar You Spend
Tracking every dollar might sound like the perfect budgeting strategy, but James argues that maintaining such a detailed system requires considerable effort.
Unexpected expenses can quickly throw a carefully calculated budget off track.
Instead, Patrick suggests focusing on broader spending categories, including:
- Mortgage or rent repayments.
- Groceries and household essentials.
- Utilities and recurring bills.
- Savings and investments.
- Discretionary spending.
James also suggests allowing some flexibility rather than allocating every dollar.
The takeaway: Your budget should reflect your financial goals without becoming unnecessarily complicated.
2. Separate Your Spending and Savings Accounts
Keeping spending and savings separate can make managing money easier, particularly for people who tend to spend whatever appears available in their bank account.
James explains that he keeps most of his money in a mortgage offset account while using an Excel spreadsheet to allocate funds towards holidays, emergencies, Christmas and household repairs.
This allows the money to remain in the offset account while still being organised for different purposes.
For those who prefer something simpler, separate bank accounts labelled according to their savings goals can work just as effectively.
Patrick also highlights the potential benefits of using an interest-free credit card alongside an offset account, provided the balance is paid in full within the interest-free period.
However, both agree that discipline is essential.
3. Automatically Transfer Savings on Payday
ASIC MoneySmart encourages Australians to build savings through automatic transfers.
While James supports the principle of paying yourself first, he questions whether fixed automatic transfers suit everyone.
Patrick shares his experience of setting up a $300 weekly savings transfer when he first started working, despite occasionally earning less than that amount.
The problem? Automatic transfers don’t always account for fluctuating income or upcoming expenses.
A more practical approach may involve reviewing your financial commitments each payday before deciding how much to save.
The takeaway: Consistent saving matters, but flexibility can prevent unnecessary financial pressure.
4. Understand Your Needs Versus Wants
Distinguishing between essential and discretionary expenses is another common budgeting recommendation.
However, Patrick and James explain that everyone’s circumstances are different.
A gym membership might seem unnecessary to one person but provide significant value to someone balancing work, health and personal commitments.
The same applies to dining out, holidays and entertainment.
Rather than eliminating everything enjoyable, identify which expenses genuinely contribute to your lifestyle.
A realistic budget should leave room for enjoyment while supporting your financial priorities.
5. Cancel Subscriptions You Barely Use
Subscription creep is one expense that can quietly affect household budgets.
Streaming services, entertainment platforms and other memberships often increase their prices gradually, making additional costs easy to overlook.
Patrick discusses cancelling several streaming subscriptions and keeping only the sports service he regularly watches.
James shares a similar strategy: rotating between streaming platforms depending on which shows his household wants to watch.
Consider reviewing your subscriptions every six or twelve months.
Ask yourself:
- Am I regularly using this service?
- Has its price increased?
- Could I temporarily pause my membership?
- Am I paying for multiple services offering similar benefits?
Small recurring expenses can become significant over time.
6. Put Money Aside for Annual Bills
This is one budgeting tip both accountants strongly support.
James uses a sinking fund to gradually save for predictable expenses throughout the year.
These might include:
- Vehicle registration and insurance.
- Council rates.
- Christmas expenses.
- Car servicing.
- Home maintenance.
Instead of waiting until a large bill arrives, calculate your expected annual expenses and regularly contribute towards them.
As James explains, saving for Christmas in January might feel unnecessary, but starting in November makes things considerably harder.
7. Set a Weekly Spending Limit
Weekly spending limits can help control discretionary purchases, but James cautions against making them too restrictive.
Some weeks naturally cost more than others.
Patrick suggests calculating your annual spending requirements and dividing the total by 52 to establish a realistic weekly allowance.
This provides a broader financial picture while accommodating fluctuations throughout the year.
The goal isn’t necessarily to spend the exact same amount every week. It’s to understand whether your overall spending remains sustainable.
8. Meal Plan and Shop Around
Both accountants agree that meal planning and comparing prices are worthwhile habits.
James regularly checks supermarket specials and compares prices between nearby stores, while Patrick prepares his weekly meals in advance.
Their discussion also extends beyond groceries to fuel, dining out and other everyday purchases.
Simple strategies include:
- Planning meals before grocery shopping.
- Comparing supermarket specials.
- Preparing lunches instead of buying them daily.
- Checking fuel prices where practical.
- Comparing prices before larger purchases.
Convenience has value, but understanding what you’re paying for it can help you make better spending decisions.
9. Round Up Purchases Into Savings
Round-up savings tools automatically allocate small amounts towards savings or investments whenever you make a purchase.
For example, spending $4.50 on coffee could trigger an additional 50-cent contribution, rounding the transaction up to $5.
James considers this a useful introduction to saving and investing, particularly for people unfamiliar with financial markets.
However, Patrick raises an interesting concern: could these tools unintentionally encourage additional spending?
The important distinction is that round-up contributions should complement responsible spending habits, not become an excuse to purchase more.
10. Review Your Budget Regularly
A budget shouldn’t remain unchanged when your financial circumstances change.
Both accountants recommend reviewing your budget at least annually, with additional adjustments whenever significant expenses increase.
Examples include changes to:
- Mortgage interest rates.
- Fuel prices.
- Household income.
- Insurance premiums.
- Recurring living expenses.
James highlights how maintaining a spreadsheet can make these adjustments easier.
Rather than rebuilding your entire budget, updating a few figures can help you understand how changing costs affect your financial position.
What Makes a Budget Actually Work?
The biggest lesson from Patrick and James discusses that budgeting isn’t about following every financial rule perfectly.
It’s about understanding your goals and developing habits you can realistically maintain.
Someone focused on accelerating their savings may require a more structured approach than someone prioritising lifestyle flexibility.
Likewise, a budgeting strategy that works for a homeowner with an offset account might not suit someone earning an irregular income.
The most effective budget is one that helps you make informed financial decisions without making everyday life unnecessarily difficult.

Frequently Asked Questions About ASIC’s Budgeting Tips
Do I need to track every dollar to budget effectively?
Not necessarily. Tracking broader spending categories can provide useful financial visibility without requiring you to record every individual transaction.
How often should I review my personal budget?
At least annually, although reviewing it whenever your income or major expenses change can help keep your budget realistic.
Is it better to have separate savings accounts?
Separate accounts can make savings goals easier to manage. However, homeowners with offset facilities may prefer tracking different savings allocations within their offset account.
What is a sinking fund?
A sinking fund involves regularly setting aside money for anticipated future expenses, such as insurance, vehicle registration, Christmas or household maintenance.
Are automatic savings transfers worth using?
They can help establish consistent saving habits, particularly when income is predictable. However, people with fluctuating income may benefit from adjusting contributions according to their upcoming financial commitments.
Get Your Finances Moving in the Right Direction
Managing money effectively starts with understanding your financial position and making informed decisions.
At Latitude Accountants, we believe good financial advice should be practical, proactive and focused on helping you achieve your goals.
Whether you’re managing personal finances or running a business, our team is here to help you navigate your accounting and tax obligations with confidence.
Accounting Done Right. The Latitude Way.
📍 Sydney Olympic Park | Marrickville | Melbourne | Loxton | Adelaide
📞 1300 706 597
📧 info@latitudeaccountants.com.au
Disclaimer
This article provides general information only and does not constitute financial, tax, accounting, legal, property or business advice. Individual circumstances vary, and you should seek guidance from an appropriately qualified adviser before making financial decisions. References to ASIC MoneySmart are included for educational and discussion purposes and do not imply endorsement of Latitude Accountants by ASIC.
Free Consultation
Got questions after reading this?
Book a call with our team. We'll walk through your situation and help you understand your options — no obligation.
Book Your Free Consultation*Free for all ABN holders · Limited spots available
Call 1300 706 597What We Do
Chartered accountants who work proactively
Not just at tax time — all year round.
Before You Make a Move
Six times you should call us first
Most costly mistakes happen before the paperwork is signed.
Buying a vehicle
Structure, FBT, and depreciation all need to be right before you sign.
Taking money out
Wages, dividends, or drawings each carry different tax consequences.
Buying property
Who buys it changes your GST, land tax, and CGT position entirely.
Hiring your first employee
Payroll, super, and STP obligations kick in from day one.
Buying or selling a business
You can inherit someone else's tax debt. Know what you're buying first.
Taking on a partner
Equity splits need proper structure upfront. A handshake deal costs more to unwind.
Get In Touch
Stop Guessing. Start Making Better Decisions.
Get clarity on your numbers, your structure, and your next move. Speak directly with our team and walk away knowing exactly where you stand.