
Guides & Resources
Super Under $250,000 in Australia? New Research Warns Retirement Savings Could Run Out Within a Decade
New research warns that Australians with less than $250,000 in super may face retirement shortfalls.
Learn what it means and how to prepare.
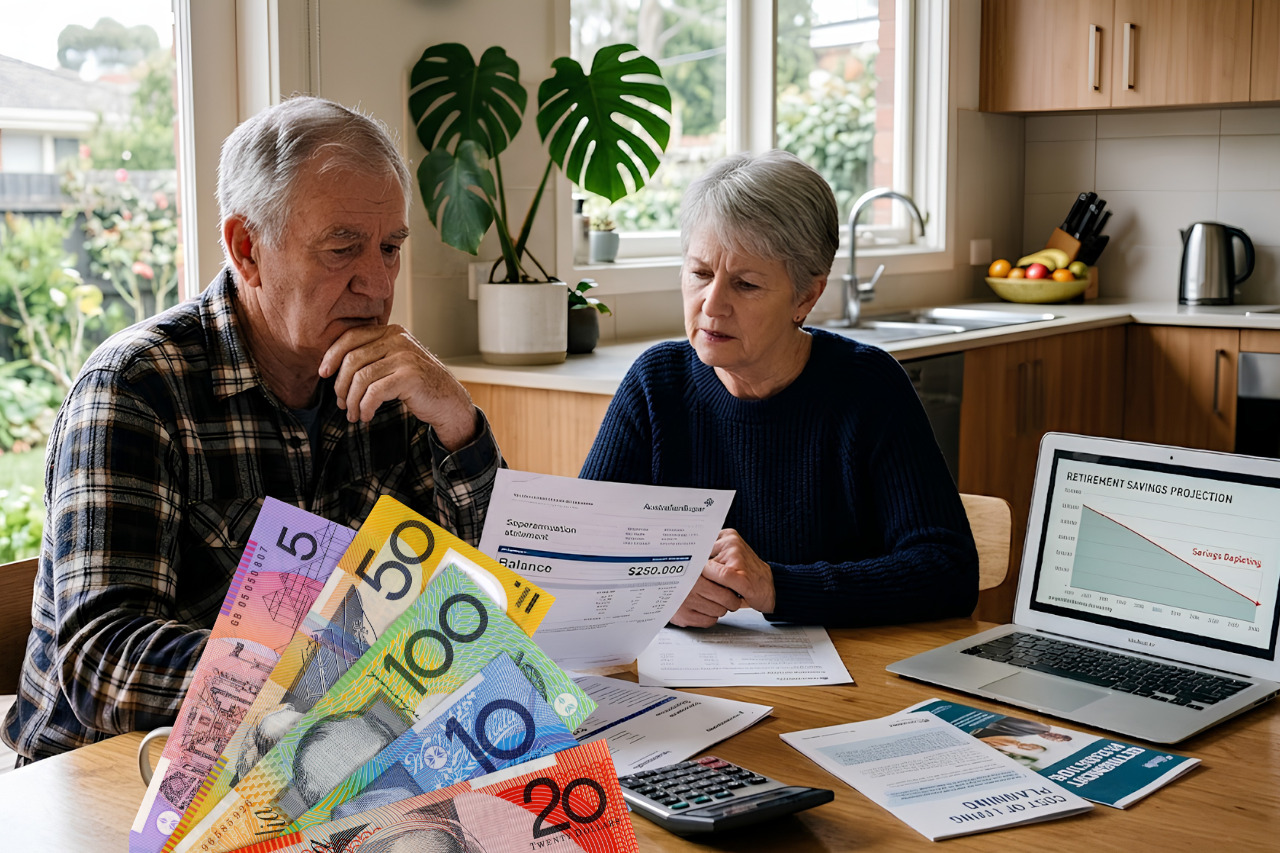

Recent retirement research has sparked renewed concern about whether Australians are adequately prepared for retirement, particularly those with lower superannuation balances.
According to analysis from the Monash Centre for Financial Studies, Australians entering retirement with less than $250,000 in super may face a higher likelihood of exhausting their retirement savings within around a decade if they aim to maintain a comfortable standard of living.
The research also suggests that retirees may require balances closer to $400,000 or more to achieve more stable long-term retirement outcomes, depending on investment strategy, spending behaviour, and market conditions.
While these figures are based on modelling and assumptions rather than guarantees, they highlight ongoing concerns about retirement adequacy in Australia.
For employees, business owners, contractors, and retirees, the findings reinforce the importance of long-term superannuation planning and ongoing financial review.
What Happened?
A recent study by researchers from the Monash Centre for Financial Studies examined how superannuation balances, investment strategies, and market performance affect retirement sustainability.
The research modelled different scenarios based on:
- Starting superannuation balances
- Asset allocation (growth vs defensive investments)
- Market conditions in early retirement years
- Withdrawal rates used to fund living expenses
- Inflation and long-term economic assumptions
The findings suggest that retirees with lower balances, particularly those under $250,000, may face a higher risk of depleting their super if they maintain higher spending levels in retirement.
The research also found that:
- Balanced investment portfolios generally produce more stable outcomes
- Overly defensive portfolios may reduce long-term sustainability
- Higher equity exposure can improve long-term balances but increases short-term volatility
- Early retirement market losses can significantly impact long-term outcomes
Importantly, the research is based on modelling scenarios and does not predict guaranteed outcomes for individual Australians.

Why Does This Matter?
Retirement planning in Australia is becoming increasingly complex due to several long-term trends, including:
- Rising cost of living
- Longer life expectancy
- Inflation pressures
- Uncertainty in global markets
- Increasing healthcare costs in retirement
As a result, Australians are not only required to save more for retirement but also to manage how those savings are drawn down over time.
A key concern highlighted by the research is sustainability — ensuring that retirement income lasts for the full duration of retirement, which can now extend 20 to 30 years or more.
For many Australians, this raises two important risks:
- Outliving retirement savings
- Underspending in retirement due to fear of running out of money
Both scenarios can have a significant impact on the quality of life in later years.
Why Superannuation Levels Matter
While the figures in the research are not official thresholds, they provide a useful reference point for understanding retirement preparedness.
The study highlights:
- Balances under $250,000 may be more vulnerable under certain assumptions
- Balances around $400,000 may offer more stability in modelling scenarios
- Outcomes vary significantly based on spending needs and investment strategy
However, superannuation adequacy is not a one-size-fits-all calculation.
Key factors that influence retirement outcomes include:
- Home ownership status
- Lifestyle expectations
- Health and medical expenses
- Access to the Age Pension support
- Investment returns over time
- Inflation and cost-of-living changes
This means two individuals with the same super balance may experience very different retirement outcomes.
Who Should Pay Attention?
Small Business Owners
Business owners often rely on the sale of their business as part of retirement funding. However, superannuation remains a critical backup and long-term wealth component.
Employees
Regular contributions through employer super guarantee payments can accumulate significantly over time, especially when combined with additional voluntary contributions.
Contractors and Self-Employed Individuals
Without compulsory super contributions in many cases, contractors need to be particularly proactive in managing retirement savings.
Individuals Nearing Retirement
Those approaching retirement age should regularly review whether their current balance aligns with expected retirement spending needs.
Women Approaching Retirement
Research consistently shows that women may retire with lower balances due to career breaks, part-time work, and wage gaps, making planning even more important.
What Are the Superannuation and Financial Planning Implications?
Retirement Income Planning
The research reinforces the importance of understanding how superannuation translates into retirement income over time, rather than focusing only on the balance itself.
Investment Strategy in Retirement
Investment allocation plays a major role in whether savings last throughout retirement. Overly conservative portfolios may not keep pace with inflation, while overly aggressive portfolios may introduce volatility.
Contribution Strategy
Australians may need to reassess whether current contribution levels are sufficient to meet long-term retirement goals.
Withdrawal Planning
How much is withdrawn each year in retirement can significantly affect how long savings last.
Government Age Pension Interaction
For many Australians, the Age Pension will remain an important part of retirement income planning and should be factored into overall strategy.
What Should Australians Do Now?
Rather than reacting to headlines, Australians should focus on practical planning steps.
Review Your Current Super Balance
Understand where your current balance sits relative to your retirement goals.
Estimate Retirement Spending Needs
Consider what level of income you may require to maintain your desired lifestyle.
Check Contribution Levels
Review whether current contributions are sufficient to meet long-term objectives.
Assess Investment Settings
Ensure your super fund’s investment strategy aligns with your age and risk tolerance.
Consider Long-Term Planning
Superannuation should be viewed as part of a broader wealth and retirement strategy.
Seek Professional Advice
Retirement planning involves tax, investment, and lifestyle considerations that often require tailored guidance.
Common Mistakes to Avoid
Focusing Only on the Balance
Retirement adequacy depends on income needs, not just total super savings.
Assuming a Fixed Number Applies to Everyone
There is no universal superannuation target suitable for all Australians.
Ignoring Inflation
Living costs typically increase over time, reducing purchasing power.
Overly Defensive Investing
Being too conservative may reduce long-term sustainability.
Not Reviewing Super Regularly
Many Australians leave super settings unchanged for years.
Relying Solely on the Age Pension
While important, it may not fully support desired retirement lifestyles.

Frequently Asked Questions
1. Is $250,000 enough to retire in Australia?
It depends on lifestyle expectations, other income sources, and housing status. Research suggests it may be challenging for a comfortable retirement.
2. How much super do I need to retire comfortably?
There is no fixed amount. It depends on spending needs, retirement age, and personal circumstances.
3. Is $400,000 enough to retire?
Some modelling suggests it may provide more stable outcomes, but individual circumstances vary.
4. What happens if I run out of super?
You may rely on the Age Pension or other savings, depending on eligibility.
5. Should I change my super investment strategy?
Only after reviewing your goals, risk tolerance, and retirement timeline.
6. Does super last 20–30 years?
It can, depending on balance size, investment returns, and withdrawal rate.
7. Are women more affected by low super balances?
Yes, research shows women often retire with lower average balances.
8. Can I still add more to my super?
Yes, subject to contribution caps and eligibility rules.
9. Should I switch to an SMSF?
It depends on your financial situation and willingness to manage compliance responsibilities.
10. How often should I review my super?
At least annually or when your financial situation changes.
Final Thoughts
The latest superannuation research highlights an important reality for Australians: retirement planning is no longer just about reaching a target age or accumulating a single balance figure.
Instead, it requires a long-term strategy that considers investment performance, spending behaviour, inflation, and changing lifestyle needs.
While headlines may focus on specific numbers, the broader message is clear — proactive retirement planning matters more than ever.

Need Help Reviewing Your Retirement Position?
If you are unsure how this update affects your superannuation, retirement plans, tax position, or long-term financial strategy, speak with Latitude Accountants.
Our team can help you understand your options, stay compliant, and make better business decisions with confidence.
📍 Sydney Olympic Park | Marrickville | Melbourne | Loxton
📞 1300 706 597
📧 info@latitudeaccountants.com.au
Disclaimer:
This article is general information only and does not constitute tax, financial, or investment advice. It is based on publicly available reporting and research at the time of writing. Individual circumstances vary, and professional advice should be obtained before making financial decisions.
Free Consultation
Got questions after reading this?
Book a call with our team. We'll walk through your situation and help you understand your options — no obligation.
Book Your Free Consultation*Free for all ABN holders · Limited spots available
Call 1300 706 597What We Do
Chartered accountants who work proactively
Not just at tax time — all year round.
Before You Make a Move
Six times you should call us first
Most costly mistakes happen before the paperwork is signed.
Buying a vehicle
Structure, FBT, and depreciation all need to be right before you sign.
Taking money out
Wages, dividends, or drawings each carry different tax consequences.
Buying property
Who buys it changes your GST, land tax, and CGT position entirely.
Hiring your first employee
Payroll, super, and STP obligations kick in from day one.
Buying or selling a business
You can inherit someone else's tax debt. Know what you're buying first.
Taking on a partner
Equity splits need proper structure upfront. A handshake deal costs more to unwind.
Get In Touch
Stop Guessing. Start Making Better Decisions.
Get clarity on your numbers, your structure, and your next move. Speak directly with our team and walk away knowing exactly where you stand.